


Reviewed by ThaiLawOnline, a licensed Thai law firm practising in Thailand since 2006. Thai lawyer of record: Wichuda Atthamethakon, LL.M., Thai Bar Licence 3149/2556.
Last updated on September 15, 2026
You moved to Thailand, or you plan to. You found the right visa, opened a bank account, and signed a lease. Then someone at the immigration counter asks for your health insurance documents. What happens next depends on which visa you hold, where you bought your policy, and whether that policy meets Thailand’s specific legal thresholds.
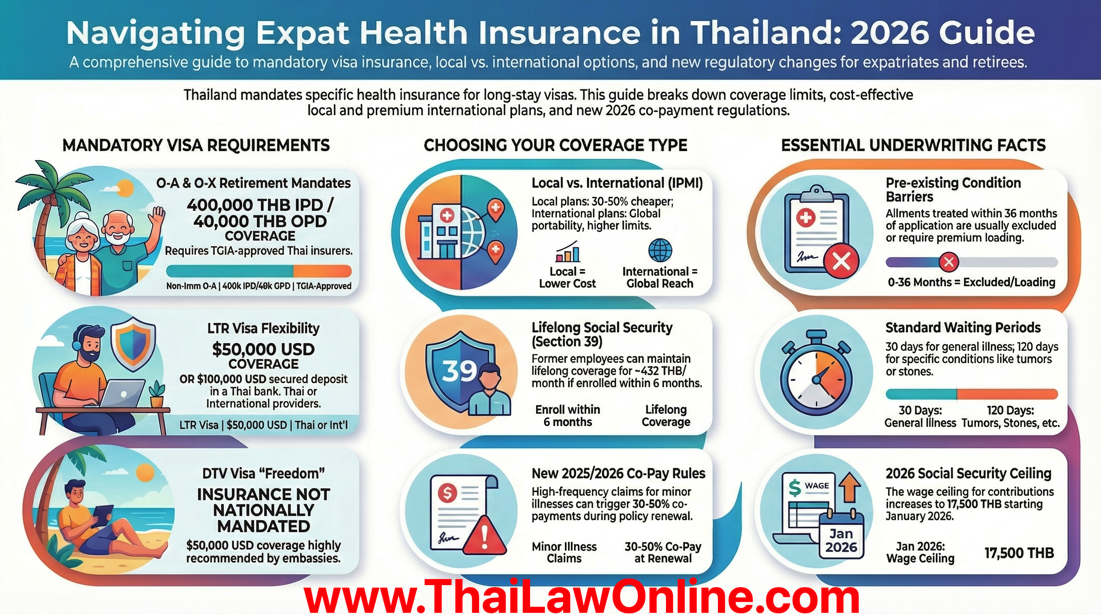
Thailand does not have a single, blanket health insurance mandate for all foreigners. The requirements vary by visa type, and the penalties for getting them wrong range from a denied extension to an uninsured hospital bill running into millions of baht. This guide breaks down the legal framework visa by visa, covers the tax deductions most expats miss, and explains how Thailand’s Social Security system works for foreign employees.
Last reviewed: 3 September 2026. The visa insurance thresholds and the Social Security figures below were checked against sources rather than carried forward. The Social Security contribution ceiling was verified as the FIRST of three phases set by the Ministerial Regulation published in the Royal Gazette on 12 December 2025 and effective 1 January 2026: 17,500 THB from 2026, 20,000 THB from 2029 and 23,000 THB from 2032, against a floor of 1,650 THB, confirmed from two independent professional summaries that are not copies of one another. The Section 40 passage was corrected because it contradicted our own Social Security guide; the instrument that settles it was then located and the passage was rewritten from it, which is the Royal Decree cited in that section below. The O-A insurance figures were then read in the primary, on the same day and by a second session: Order of the Royal Thai Police No. 654/2564, clause 2.22(6), in the Royal Gazette volume 139, special part 17 Ngor, page 16, of 24 January 2022 (that order has since been overtaken: it amended the annex of Police Order 327/2557, which was repealed with its amendments on 26 September 2023, and the same criteria now sit at clause 2.22 of the table annexed to Immigration Bureau Order 12/2568 of 23 January 2025, where the figures are unchanged), and the Ministry of Foreign Affairs operating manual for the O-A, which records the Cabinet Resolution of 15 June 2021 replacing the 40,000 and 400,000 baht split with a single sum insured. The table above was corrected to match them.
This review does not certify four things and says so rather than implying otherwise. The Social Security Act B.E. 2533 itself could not be read: the only copy in our law corpus is an empty record, so Sections 33, 39 and 40 are stated here from secondary sources and from our own Social Security guide, not from the Act. The Revenue Code deduction figures were not read against the Revenue Department registers. The list of approved insurers and the premium ranges are market practice, not law, and change without notice. And the O-A and O-X thresholds are stated as the orders cited in the text record them; the orders themselves were not re-read in this pass.
Table of Contents
Which Visas Require Health Insurance in Thailand?
Thai immigration treats health insurance as a visa compliance issue, not a general legal obligation. If you hold a tourist visa or a Non-Immigrant B (business) visa, no law forces you to carry health insurance. But for retirement visas, long-term resident visas, and certain specialty categories, the rules are specific and enforced.
Non-Immigrant O-A Visa (One-Year Retirement)
Since 31 October 2019 an O-A applicant, and an O-A holder extending inside Thailand, must show health insurance. The amount was raised in 2021 and 2022, and the superseded figures are still widely quoted, including by insurers. The requirement is now a single total sum insured rather than an outpatient and inpatient split:
| Period | Minimum sum insured | Approximate USD |
|---|---|---|
| New applications from 1 October 2021; extensions inside Thailand from 1 October 2022 | Not less than 3,000,000 THB, covering the whole period of stay | ~$100,000 |
| 31 October 2019 until those dates (superseded, do not buy to this figure) | 40,000 THB outpatient and 400,000 THB inpatient per policy year | ~$1,100 / ~$11,600 |
The policy must cover the full duration of your stay. The rule runs on two separate tracks, and they do not say the same thing. At issuance abroad, the Ministry of Foreign Affairs has accepted Thai or non-Thai insurers since 31 October 2019. At extension inside Thailand, clause 2.22 of the table annexed to Immigration Bureau Order 12/2568 of 23 January 2025 expressly permits an O-A holder to choose Thai cover, non-Thai cover or foreign state welfare, and applies one threshold to all three: not less than USD 100,000 or 3,000,000 THB, covering the whole period of stay. ⚠️ Two conditions in that clause decide how you buy the cover, and most guidance omits them. Sub-clause (6.1) requires a Thai policy to be purchased online through longstay.tgia.org, so an OIC-approved policy bought some other way can still be queried at the counter. Sub-clause (6.2) gives foreign cover and foreign state welfare two certification routes, not one: certification by that country’s embassy in Thailand, or a notarised certification of the signatory’s signature obtained through your own Ministry of Foreign Affairs. Sub-clause 6.3 of the same table covers the case an older applicant is most likely to meet, an insurer refusing cover in whole or in part: a deposit of not less than 3,000,000 THB in a Thai commercial bank, held for at least two months before the application, or a deposit plus other health cover totalling not less than 3,000,000 THB, with the refusal certified by the insurer, by that country’s embassy in Thailand, or by a notary through your own Ministry of Foreign Affairs. A foreign policy must be certified or notarised through your own Ministry of Foreign Affairs in the format prescribed by the Ministry of Public Health. That is a documentary hurdle, not a bar. An OIC-approved Thai policy remains the path of least resistance at the counter, but you are not legally obliged to abandon good international cover in order to extend.
Legal basis: Issuance abroad: Ministry of Foreign Affairs criteria effective 31 October 2019, amended from 1 October 2021 following the Cabinet Resolution of 15 June 2021. Extension inside Thailand: clause 2.22 of the table annexed to Immigration Bureau Order 12/2568 of 23 January 2025. The rule reached that table by a chain worth knowing, because almost everything written in English still stops at the first link: Royal Thai Police Order 654/2564 and Immigration Bureau Order 312/2564, both given 27 December 2021 and effective 1 October 2022 (Royal Gazette 2565/E/017), were overtaken when Police Order 327/2557 was repealed with its amendments on 26 September 2023 and Immigration Bureau Order 242/2566 expressly repealed Order 312/2564. The figures did not change; the instrument to cite did. The approved Thai insurer list is maintained by the Office of Insurance Commission (OIC).
Non-Immigrant O-X Visa (Ten-Year Retirement)
Do not assume O-X carries the same insurance minimum as O-A. The O-X base requirement is a Thai policy approved by the Office of Insurance Commission at not less than 40,000 THB outpatient and 400,000 THB inpatient per policy year, as published by the Thai General Insurance Association and the Ministry of Foreign Affairs. Since 1 October 2021 a COVID layer with a total sum insured of 3,000,000 THB or USD 100,000 has been applied by several consular posts to the O-X as well, and at least one post accepts foreign insurers for O-X using the Foreign Insurance Certificate. Official sources are not uniform here, so confirm with the post handling your application. The O-X also requires higher financial qualifications (3 million THB in deposits, or 1.8 million plus annual income of 1.2 million THB per year), and the full 3 million THB must be accumulated in a Thai bank account within one year of entry.
Non-Immigrant O Visa (Extension Based on Retirement or Marriage)
Here is the gap that confuses many retirees: if you entered Thailand on a Non-Immigrant O visa (not O-A) and extend your stay based on retirement or a Thai spouse, Thai immigration does not require health insurance as a condition of that extension. The mandatory insurance rule applies to the O-A and O-X categories specifically.
Practical warning: Some immigration offices have started asking O visa holders for insurance documents during extensions, even without a legal mandate. Officers have discretion. Carrying a valid policy avoids delays and arguments at the counter, even when the law does not require it.
Long-Term Resident (LTR) Visa
The LTR visa, administered by the Board of Investment (BOI), requires health insurance covering at least USD 50,000 in medical expenses. The policy must have at least 10 months of remaining validity at the time of application. Applicants who receive Thai Social Security benefits or who maintain at least USD 100,000 in a Thai bank account for 12 months can satisfy this requirement without buying a separate policy.
Unlike the O-A visa, the LTR accepts international health insurance policies. Thai insurers work, too. The BOI reviews the policy documents during the application process. See our LTR Visa guide for full eligibility details.
SMART Visa
SMART visa holders need international-level health insurance, though the regulations do not specify a fixed baht amount the way the O-A rules do. In practice, policies providing at least USD 50,000 in coverage satisfy the requirement. The BOI reviews each application individually.
Work Permits and Non-Immigrant B Visas
Thai labor law does not require employers to provide private health insurance. But foreign employees who hold work permits and earn wages in Thailand contribute to the Social Security Fund. That contribution buys access to public healthcare through the Section 33 system, which we explain below.
Thailand’s Approved Health Insurers for Visa Compliance
For O-A and O-X visa holders, the Office of Insurance Commission (OIC) maintains a list of approved Thai insurance companies. A policy from one of these companies is the simplest way to satisfy immigration, and it is what most extension applicants use. It is not the only lawful route: clause 2.22 of the table annexed to Immigration Bureau Order 12/2568 of 23 January 2025 also provides for foreign policies and state social-welfare cover. There are two ways to certify them and most guides mention only the second: the document list at item 5.2 accepts cover certified either by that country’s embassy in Thailand or by a notarised certificate of the signatory’s signature from your own Ministry of Foreign Affairs, in the form the Ministry of Public Health prescribes. For someone already in Thailand the embassy route is usually the shorter one. The OIC list includes both Thai-owned and international insurers licensed to operate in Thailand:
- Pacific Cross Health Insurance
- AXA Insurance Thailand
- LMG Insurance
- The Viriyah Insurance
- Falcon Insurance
- Thaivivat Insurance
- Navakij Insurance
- Dhipaya Insurance
- Asia Insurance
- Aetna Health Insurance (Thailand)
- Sompo Insurance (Thailand)
Premiums vary based on your age, pre-existing conditions, and the scope of coverage you choose beyond the visa minimums. A 60-year-old retiree with no pre-existing conditions can expect annual premiums between 20,000 and 60,000 THB for a visa-compliant policy. Older applicants with health histories may face premiums above 100,000 THB, and some insurers decline applicants over 75.
If you hold an LTR or SMART visa, you can use any insurer (Thai or international) that meets the USD 50,000 coverage threshold.
Social Security for Foreign Workers: Section 33 Healthcare
If you work for a Thai employer with a valid work permit, you contribute to Thailand’s Social Security Fund under Section 33 of the Social Security Act B.E. 2533 (1990). Both you and your employer contribute 5% of your monthly salary, capped at a salary ceiling of 17,500 THB since 1 January 2026. That means the maximum monthly contribution is 875 THB from you and 875 THB from your employer.
Read 17,500 THB as a first step rather than a settled figure. The Ministerial Regulation published in the Royal Gazette on 12 December 2025 raises the ceiling in three phases: 17,500 THB from 2026, 20,000 THB from 2029 and 23,000 THB from 2032, taking the maximum monthly contribution from 875 THB to 1,000 THB and then to 1,150 THB on each side. The floor is unchanged at 1,650 THB a month. If you are budgeting employer cost over the life of a lease or a business plan, budget the phases. Our guide to Social Security in Thailand carries the full table and the benefit figures that move with it.
Section 33 entitles you to free medical treatment at a designated hospital that you select during enrollment. The coverage includes outpatient visits, inpatient care, prescribed medications, and maternity benefits. You receive treatment at your assigned hospital at no additional cost. If you go to a different hospital without a referral or emergency justification, Social Security does not cover the bill.
Section 39: Voluntary Continuation After You Leave a Job
Foreign workers who contributed to Section 33 for more than 12 months can switch to Section 39 after leaving employment. You continue contributing 432 THB per month and retain healthcare benefits at your designated hospital. You lose unemployment coverage and receive reduced pension accruals compared to Section 33. To qualify, you must remain in Thailand on a valid visa (retirement, marriage, or other long-stay category) and apply within six months of leaving your job.
Legal basis: Social Security Act B.E. 2533 (1990), Sections 33 and 39. Foreign nationals with valid work permits are treated identically to Thai employees for Social Security purposes.
Section 40: Why It Is Not Your Answer Either
Section 40 is the voluntary scheme for self-employed and informal workers who fall outside Sections 33 and 39. It is closed to ordinary foreign nationals, and the bar sits in a Royal Decree rather than in the Act. Section 40 itself sets no nationality condition: it delegates the qualifications to a Royal Decree, which is why reading the Act alone answers this question wrongly. The Royal Decree Prescribing the Qualifications of Persons Who May Apply to Become an Insured Person B.E. 2561, published in the Royal Gazette on 27 March 2018 and amended in 2020, requires an applicant to hold Thai nationality, or to be a stateless or displaced person holding a Thai-issued non-national identity card, and to be aged between 15 and 65. A foreigner living here on a retirement, marriage, DTV or LTR visa holds none of those statuses. The practical point is the one that matters for insurance planning: no immigration category accepts Section 40 cover in place of the policy a visa requires, and its benefits are far narrower than Section 33’s. If you direct your own Thai company without a standard employment contract, your realistic routes are Section 33 through a genuine payroll, or private insurance.
Tax Deductions on Health Insurance Premiums
Thai tax residents can deduct health insurance premiums from their personal income tax. The Revenue Code allows two deductions:
| Deduction Type | Maximum | Condition |
|---|---|---|
| Your own health insurance | 25,000 THB/year | Policy from a Thai-licensed insurer |
| Parents’ health insurance | 15,000 THB/year | Covers your parents or spouse’s parents; parents must earn less than 30,000 THB/year |
The combined total of life insurance and health insurance deductions cannot exceed 100,000 THB per year. If you pay 80,000 THB in life insurance premiums, you can only deduct up to 20,000 THB for health insurance, not the full 25,000.
To claim the deduction, the insurer must be licensed in Thailand. International policies purchased from overseas companies do not qualify, even if they cover you while living in Thailand. Keep your premium receipts and the insurer’s tax certificate (issued annually) for filing with the Revenue Department.
Common Pitfalls Expats Face with Thai Health Insurance
Buying the Wrong Policy for Your Visa Type
International policies from Cigna, Allianz, or BUPA purchased outside Thailand satisfy most LTR and SMART visa applications. For an O-A extension they can also be used, but only via the certification route in clause 2.22 of the table annexed to Immigration Bureau Order 12/2568 of 23 January 2025: at item 5.2 the policy must be certified either by that country’s embassy in Thailand or by a notarised certificate of the signatory’s signature from your own Ministry of Foreign Affairs, in the form the Ministry of Public Health prescribes. Retirees run into trouble every year not because foreign cover is forbidden, but because they arrive at the counter with an uncertified foreign policy and no time left to fix it. Decide early which route you are taking.
Gaps in Coverage During Visa Transitions
If you switch from a work permit to a retirement visa, your Section 33 coverage ends when your employment terminates. You need private insurance before your O-A or O-X extension comes due. The transition period between employment and retirement leaves many expats uninsured for weeks or months.
Age-Related Coverage Denials
Most Thai insurers cap new enrollment at age 70 or 75. Existing policyholders can often renew past those ages, but new applicants cannot get coverage. If you arrive in Thailand at 73 planning to apply for an O-A visa, you may find that no approved insurer will sell you a policy. The workaround: apply for a Non-Immigrant O visa instead, which has no insurance mandate, or secure an international policy and apply from abroad where embassy requirements may differ.
Pre-Existing Condition Exclusions
Thai insurance policies routinely exclude pre-existing conditions for the first 12 to 24 months. Your policy meets the visa minimums on paper, but an actual hospital stay related to a pre-existing condition produces a claim denial. You pay out of pocket. Budget accordingly.
Relying on Social Security Alone
Section 33 covers treatment at one designated public hospital. The quality of care varies. Wait times at public hospitals can stretch to hours. Many foreign workers supplement Social Security with a private policy that covers private hospitals like Bumrungrad, Bangkok Hospital, or Samitivej.
Private vs. Public Healthcare: The Cost Gap
Thailand’s private hospitals charge international-grade prices. A night in a private room at Bumrungrad International runs 15,000 to 40,000 THB. Heart surgery at a private hospital can cost 500,000 to 2,000,000 THB. At a public hospital covered by Social Security, the same procedures cost a fraction of that amount, but you face longer waits and shared wards.
Private health insurance premiums in Thailand range from 15,000 THB per year for a healthy 35-year-old to 200,000+ THB per year for a 70-year-old with full coverage. The visa-minimum policies are bare-bones. For real protection against a major health event, most financial advisors recommend inpatient coverage of at least 2,000,000 to 5,000,000 THB.
Frequently Asked Questions
Is health insurance mandatory for all foreigners in Thailand?
No. The mandate applies to specific visa categories. O-A and O-X retirement visa holders must carry qualifying health insurance. LTR visa holders must show USD 50,000+ in coverage or maintain a USD 100,000 bank deposit. Tourist visa holders, Non-Immigrant B holders, and Non-Immigrant O extension holders face no formal insurance requirement.
What are the minimum coverage amounts for the O-A retirement visa?
Total coverage of at least 3,000,000 THB, or USD 100,000. This replaced the old split requirement of 40,000 THB outpatient and 400,000 THB inpatient, for new applications from 1 October 2021 and, at extension inside Thailand, from 1 October 2022, and the rule now sits at clause 2.22 of the table annexed to Immigration Bureau Order 12/2568 of 23 January 2025. The policy may be Thai or foreign; foreign cover must be certified by that country’s embassy in Thailand, or notarised through your own Ministry of Foreign Affairs. It must cover the full period of your stay.
Can I use international health insurance for a Thai visa?
Yes, subject to paperwork. For initial O-A or O-X applications at Thai embassies abroad, Thai or non-Thai insurers have been accepted since 31 October 2019. For annual O-A extensions inside Thailand, Clause 2.22 of the table annexed to Immigration Bureau Order 12/2568 of 23 January 2025 permits foreign cover at not less than USD 100,000, provided it is certified by that country’s embassy in Thailand or notarised through your own Ministry of Foreign Affairs. A Thai OIC-approved policy is simpler, but it is not the only lawful option. LTR and SMART visa applicants can use international policies if they provide at least USD 50,000 in medical coverage.
Can I deduct health insurance premiums from my Thai taxes?
Yes. Thai tax residents can deduct up to 25,000 THB per year in health insurance premiums, provided the policy comes from a Thai-licensed insurer. The combined life and health insurance deduction cap is 100,000 THB. You can also deduct up to 15,000 THB for premiums paid for your parents or your spouse’s parents.
Do foreign workers get public healthcare through Social Security?
Foreign employees with valid work permits who contribute to the Social Security Fund under Section 33 receive free healthcare at a designated hospital. Both employer and employee contribute 5% of wages, capped at a salary of 17,500 THB per month since 1 January 2026. Coverage includes outpatient visits, inpatient care, medications, and maternity benefits.
What happens if my insurance lapses during my visa period?
For O-A and O-X holders, a lapsed policy puts your extension at risk. Immigration can deny your next extension or revoke your current permission to stay. Renew your policy before it expires and carry proof of continuous coverage to every immigration appointment.
Next Steps: Getting the Right Coverage
Start with your visa type. That determines whether insurance is mandatory, which insurers qualify, and what minimums apply. If you hold an O-A or O-X visa, get a policy from an OIC-approved Thai insurer before your next extension date. If you hold an LTR or SMART visa, verify your international policy meets the USD 50,000 threshold. If you work on a Thai work permit, check your Section 33 enrollment and consider supplementing with private coverage for access to private hospitals.
Review your policy against the actual risk, not the visa minimum. A 400,000 THB inpatient cap covers less than one night in a private hospital ICU. For long-term residents, a policy with 2,000,000 to 5,000,000 THB in inpatient coverage provides realistic protection.
If you file Thai taxes, claim your premium deduction. Keep your receipts and request a tax certificate from your insurer each year.
Need help choosing the right insurance for your visa?
ThaiLawOnline.com provides legal consultations on visa compliance, insurance requirements, and tax planning for expats in Thailand.
Links : Thailand Immigration Bureau
Health insurance is a condition of several long stay permissions, including the retirement extension. Our Thai immigration overview sets out which permission carries which requirement.
Thai Law Updates, free by email
Plain-English updates on Thai law changes that affect foreigners: property, visas, marriage, business and wills. One short email a month from a firm practicing since 2006. No spam, unsubscribe anytime.