


Reviewed by Wichuda Atthamethakon, LL.M., Thai Bar Licence 3149/2556, for ThaiLawOnline, a Thai law firm acting for foreigners since 2006.
Update log
- 4 November 2026: Added the statute box with Thai, English and French text and checked the page against the official text
Dissolution and liquidation filings become online-only
From 1 November 2026, dissolution and liquidation registrations for private limited companies and partnerships must be submitted through DBD Biz Regist. Paper walk-in filing will no longer be accepted. The online-only rule does not change the shareholder resolution, creditor notice, fourteen-day registration deadlines, accounting work or Revenue Department requirements. A company close to a deadline should prepare the online filing and signing arrangements before the resolution takes effect. Read the official DBD announcement and use the DBD Biz Regist portal.
If you’re considering closing a company in Thailand, the process involves more than just ceasing operations. Thai law requires businesses to follow a formal dissolution and liquidation process, ensuring all financial and legal obligations are properly settled. Failing to meet these requirements can lead to penalties or even personal liability for company directors.
Closing follows the obligations created at formation, described in our guide to setting up a business in Thailand.
Table of Contents
Understanding the Company Dissolution Process in Thailand
Apart from the causes that operate by themselves (an event stated in the articles, expiry of a fixed term, completion of the sole undertaking, or bankruptcy: section 1236), a voluntary closure needs a special resolution of the shareholders. The Revenue Department must also be notified and the final tax returns filed. Settlements with creditors are required too. Finally, the liquidation has to be completed and registered with the Department of Business Development (DBD). Depending on the situation, dissolution can be voluntary, court-ordered, or administrative.
Types of Company Dissolution in Thailand
The most common type is voluntary dissolution, where shareholders decide to close the company. It needs a special resolution (section 1236(4)), which means at least three-quarters of the votes of the shareholders present at the meeting and entitled to vote (section 1194). The directors then become the liquidators unless the articles provide otherwise (section 1251), and the liquidator must register the dissolution with the registrar within fourteen days (section 1254).
A court-ordered dissolution can be ordered on the grounds in section 1237: a default over the statutory report or statutory meeting, failure to start business within a year of registration or a suspension for a full year, trading only at a loss with no hope of recovery, the shareholders falling to one, or any other cause that makes it impossible for the company to continue. Insolvency is a different route: a company declared bankrupt is dissolved by that fact (section 1236(5)), and its assets are handled by the Official Receiver under the Bankruptcy Act rather than by a liquidator.
Separately, the registrar can strike a defunct company off the register (sections 1273/1 to 1273/4). Where the registrar has reasonable cause to believe the company is no longer trading, it writes to ask, and if there is no answer within thirty days, or the company confirms it has stopped, it advertises in a local newspaper and sends a notice by registered post that the company will be struck off when ninety days have passed unless it shows cause; after that the registrar may strike it off (sections 1273/1 and 1273/3). In practice this is often triggered by years of unfiled financial statements. A parallel procedure applies to a company left in liquidation without a working liquidator or a final report.
The law behind this page
English
Section 1236
Full text
A limited company is dissolved: (1) In the case, if any, provided by its regulations. (2) If formed for a period of time, by the expiration of such period. (3) If formed for a single undertaking, by the termination of such undertaking. (4) By a special resolution to dissolve. (5) By the company becoming bankrupt.
ThaiLawOnline translation
Section 1194Amended on 26 July 2008
Full text
Where the law requires an act to be done by special resolution, the general meeting must pass the resolution by a majority of not less than three quarters of the total votes of the shareholders present and entitled to vote.
ThaiLawOnline translation
Section 1254
Full text
The dissolution of the partnership or company and the names of the liquidators must be registered within fourteen days after the date of dissolution by the liquidators.
ThaiLawOnline translation
Section 1253Amended on 26 July 2008
Full text
Within fourteen days from the date of dissolution or, in the case of liquidators appointed by the Court, from the date of appointment, the liquidators must: (1) Notify the public by at least one advertisement in a local paper that the partnership or company is dissolved and that its creditors must apply for payment to the liquidators, and (2) Send a similar notice by registered letter to each creditor whose name appears in the books, accounts or documents of the partnership or company.
ThaiLawOnline translation
Section 1270
Full text
As soon as the affairs of the partnership or company are fully liquidated, the liquidators shall make up an account of the liquidation showing how the liquidation has been conducted and how the property of the partnership or company has been disposed of; and thereupon shall call a general meeting for the purpose of laying before it the account and giving any explanation thereof. After the account is approved by the general meeting, the proceedings of the meeting must be registered within fourteen days from its date by the liquidators. Such registration is taken as being the end of the liquidation.
ThaiLawOnline translation
Section 1251
Full text
Upon dissolution of a partnership or company for any other cause than bankruptcy, the managing partners or directors become liquidators unless otherwise provided by the contract of partnership or by the regulations of the company. If there are no persons to be liquidators under the foregoing provision, a liquidator or liquidators shall be appointed by the Court upon the application of the Public Prosecutor or any other interested person.
ThaiLawOnline translation
Section 1237Amended on 7 February 2023
Full text
A limited company may also be dissolved by the Court on the following grounds: (1) If default is made in filing the statutory report or in holding the statutory meeting. (2) If the company does not commence business within a year from the date of registration or suspends its business for a whole year. (3) If the business of the company can only be carried on at a loss and there is no prospect of its fortunes being retrieved. (4) If the number of the shareholders is reduced to one only. (5) If there is any other circumstance which makes it impossible for the company to continue in existence. However, in the case of default in filing the statutory report or in holding the statutory meeting, the Court may, instead of dissolving the company, direct that the statutory report be filed or the statutory meeting be held, as it may think fit.
ThaiLawOnline translation
Section 72 Revenue Code
Full text
In the case where a company or juristic partnership is dissolved, the liquidator and the manager shall have a joint duty to notify the assessment officer of the dissolution of that company or juristic partnership within fifteen days from the date on which the registrar registers the dissolution. If such persons fail to comply, the assessment officer may order the company or juristic partnership to pay additional tax of 1 time the amount of tax payable; such money shall be deemed tax. In the case where a company or juristic partnership is dissolved as aforesaid, for the purpose of computing tax, the date on which the registrar registers the dissolution shall be deemed the last day of the accounting period. The liquidator and the manager shall have a joint duty and liability to file returns and pay tax in the form and within the time prescribed in section 68 and section 69 mutatis mutandis. If the liquidator and the manager are unable to file returns and pay tax within the time under the preceding paragraph, and have filed a petition with the Director-General within thirty days from the date on which the registrar registers the dissolution, the Director-General, upon consideration that it is appropriate, may order an extension of the time; and in the case only where there is a liquidation, the Director-General may also order an extension of the accounting period. In the case where a juristic partnership is dissolved without liquidation, the managing partner of the juristic partnership shall have the same duties and responsibilities as a liquidator, jointly with the partners having power of management, as provided in the three preceding paragraphs.
ThaiLawOnline translation
ไทย
มาตรา 1236
ข้อความเต็ม
อันบริษัทจำกัดย่อมเลิกกันด้วยเหตุดังจะกล่าวต่อไปนี้ คือ(๑) ถ้าในข้อบังคับของบริษัทมีกำหนดกรณีอันใดเป็นเหตุที่จะเลิกกันเมื่อมีกรณีนั้น(๒) ถ้าบริษัทได้ตั้งขึ้นไว้เฉพาะกำหนดกาลใด เมื่อสิ้นกำหนดกาลนั้น(๓) ถ้าบริษัทได้ตั้งขึ้นเฉพาะเพื่อทำกิจการอย่างหนึ่งอย่างใดแต่อย่างเดียว เมื่อเสร็จการนั้น(๔) เมื่อมีมติพิเศษให้เลิก(๕) เมื่อบริษัทล้มละลาย
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 1194แก้ไขเมื่อ 26 กรกฎาคม 2551
ข้อความเต็ม
การใดที่กฎหมายกำหนดให้ต้องทำโดยมติพิเศษ ที่ประชุมใหญ่ต้องลงมติในเรื่องนั้นโดยคะแนนเสียงข้างมากไม่ต่ำกว่าสามในสี่ของจำนวนเสียงทั้งหมดของผู้ถือหุ้นที่มาประชุมและมีสิทธิออกเสียงลงคะแนน
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 1254
ข้อความเต็ม
การเลิกหุ้นส่วนหรือบริษัทนั้น ผู้ชำระบัญชีต้องนำบอกให้จดทะเบียนภายในสิบสี่วันนับแต่วันที่เลิกกัน และในการนี้ต้องระบุชื่อผู้ชำระบัญชีทุก ๆ คนให้จดลงทะเบียนไว้ด้วย
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 1253แก้ไขเมื่อ 26 กรกฎาคม 2551
ข้อความเต็ม
ภายในสิบสี่วันนับแต่ได้เลิกห้างเลิกบริษัท หรือถ้าศาลได้ตั้งผู้ชำระบัญชีนับแต่วันที่ศาลตั้ง ผู้ชำระบัญชีต้องกระทำดังจะกล่าวต่อไปนี้ คือ(๑) บอกกล่าวแก่ประชาชนโดยประกาศโฆษณาในหนังสือพิมพ์แห่งท้องที่อย่างน้อยหนึ่งคราวว่าห้างหุ้นส่วนหรือบริษัทนั้นได้เลิกกันแล้วและให้ผู้เป็นเจ้าหนี้ทั้งหลายยื่นคำทวงหนี้แก่ผู้ชำระบัญชี(๒) ส่งคำบอกกล่าวอย่างเดียวกันเป็นจดหมายลงทะเบียนไปรษณีย์ไปยังเจ้าหนี้ทั้งหลายทุก ๆ คนบรรดามีชื่อปรากฏในสมุด บัญชี หรือเอกสารของห้างหรือบริษัทนั้น
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 1270
ข้อความเต็ม
เมื่อการชำระบัญชีกิจการของห้างหุ้นส่วนหรือบริษัทสำเร็จลง ผู้ชำระบัญชีต้องทำรายงานการชำระบัญชีแสดงว่า การชำระบัญชีนั้นได้ดำเนินไปอย่างใด และได้จัดการทรัพย์สินของห้างหุ้นส่วนหรือบริษัทนั้นไปประการใด แล้วให้เรียกประชุมใหญ่เพื่อเสนอรายงานนั้น และชี้แจงกิจการต่อที่ประชุมเมื่อที่ประชุมใหญ่ได้ให้อนุมัติรายงานนั้นแล้ว ผู้ชำระบัญชีต้องนำข้อความที่ได้ประชุมกันนั้นไปจดทะเบียนภายในสิบสี่วันนับแต่วันประชุม เมื่อได้จดทะเบียนแล้วดังนี้ให้ถือว่าเป็นที่สุดแห่งการชำระบัญชี
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 1251
ข้อความเต็ม
ห้างหุ้นส่วนก็ดี บริษัทก็ดี ในเมื่อเลิกกันเพราะเหตุอื่นนอกจากล้มละลาย หุ้นส่วนผู้จัดการห้าง หรือกรรมการของบริษัทย่อมเข้าเป็นผู้ชำระบัญชี เว้นไว้แต่ข้อสัญญาของห้างหรือข้อบังคับของบริษัทจะมีกำหนดไว้เป็นสถานอื่น ถ้าไม่มีผู้ชำระบัญชีดังว่ามานี้ และเมื่อพนักงานอัยการหรือบุคคลอื่นผู้มีส่วนได้เสียในการนี้ร้องขอ ท่านให้ศาลตั้งผู้ชำระบัญชี
ข้อความจากฐานข้อมูลประมวลกฎหมายของเรา โปรดตรวจสอบกับข้อความทางการ (Thai text from our annotated code. Check it against the official text.)
มาตรา 1237แก้ไขเมื่อ 7 กุมภาพันธ์ 2566
ข้อความเต็ม
นอกจากนี้ศาลอาจสั่งให้เลิกบริษัทจำกัดด้วยเหตุต่อไปนี้ คือ (๑) ถ้าทำผิดในการยื่นรายงานประชุมตั้งบริษัท หรือทำผิดในการประชุมตั้งบริษัท (๒) ถ้าบริษัทไม่เริ่มทำการภายในปีหนึ่งนับแต่วันจดทะเบียน หรือหยุดทำการถึงปีหนึ่งเต็ม (๓) ถ้าการค้าของบริษัททำไปก็มีแต่ขาดทุนอย่างเดียว และไม่มีทางหวังว่าจะกลับฟื้นตัวได้ (๔) ถ้าจำนวนผู้ถือหุ้นลดน้อยลงจนเหลือเพียงคนเดียว (๕) เมื่อมีเหตุอื่นใดทำให้บริษัทนั้นไม่สามารถที่จะดำรงคงอยู่ต่อไปได้ แต่อย่างไรก็ดี ในกรณีทำผิดในการยื่นรายงานประชุมตั้งบริษัท หรือทำผิดในการประชุมตั้งบริษัท ศาลจะสั่งให้ยื่นรายงานประชุมตั้งบริษัท หรือให้มีการประชุมตั้งบริษัทแทนสั่งให้เลิกบริษัทก็ได้ แล้วแต่จะเห็นควร
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 72 ประมวลรัษฎากร
ข้อความเต็ม
ในกรณีที่บริษัทหรือห้างหุ้นส่วนนิติบุคคลเลิกกัน ให้ผู้ชำระบัญชีและผู้จัดการมีหน้าที่ร่วมกันแจ้งให้เจ้าพนักงานประเมินทราบการเลิกของบริษัทหรือห้างหุ้นส่วนนิติบุคคลนั้นภายในสิบห้าวันนับแต่วันที่เจ้าพนักงานรับจดทะเบียนเลิก ถ้าบุคคลดังกล่าวแล้วไม่ปฏิบัติตาม เจ้าพนักงานประเมินอาจสั่งให้บริษัทหรือห้างหุ้นส่วนนิติบุคคลนั้นเสียเงินภาษีเพิ่มขึ้นอีก ๑ เท่าของจำนวนภาษีที่ต้องเสีย เงินนี้ให้ถือเป็นค่าภาษี ในกรณีที่บริษัทหรือห้างหุ้นส่วนนิติบุคคลเลิกกันดังกล่าวแล้ว เพื่อประโยชน์ในการคำนวณภาษี ให้ถือว่าวันที่เจ้าพนักงานรับจดทะเบียนเลิกเป็นวันสุดท้ายของรอบระยะเวลาบัญชี ให้ผู้ชำระบัญชีและผู้จัดการมีหน้าที่และความรับผิดร่วมกันในการยื่นรายการและเสียภาษีตามแบบและภายในกำหนดเวลาที่กำหนดไว้ในมาตรา ๖๘ และมาตรา ๖๙ โดยอนุโลม ถ้าผู้ชำระบัญชีและผู้จัดการไม่สามารถยื่นรายการและเสียภาษีภายในกำหนดเวลาตามความในวรรคก่อนได้ และได้ยื่นคำร้องต่ออธิบดีภายในสามสิบวัน นับแต่วันที่เจ้าพนักงานรับจดทะเบียนเลิก เมื่ออธิบดีพิจารณาเห็นสมควรจะสั่งให้ขยายระยะเวลาออกไปอีกก็ได้ เฉพาะกรณีที่มีการชำระบัญชี อธิบดีจะสั่งให้ขยายรอบระยะเวลาบัญชีออกไปอีกด้วยก็ได้ ในกรณีที่ห้างหุ้นส่วนนิติบุคคลเลิกกันโดยไม่มีการชำระบัญชี ให้ผู้จัดการหุ้นส่วนนิติบุคคลมีหน้าที่และความรับผิดชอบเช่นเดียวกับผู้ชำระบัญชี ร่วมกับผู้เป็นหุ้นส่วนซึ่งมีอำนาจจัดการตามที่บัญญัติไว้ในสามวรรคก่อน
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
Français
Article 1236
Une société à responsabilité limitée est dissoute dans les cas suivants : (1) lorsque survient un cas que ses statuts prévoient comme cause de dissolution ; (2) à l'expiration de la durée pour laquelle elle a été constituée ; (3) à l'achèvement de l'entreprise unique pour laquelle elle a été constituée ; (4) par résolution spéciale de dissolution ; (5) en cas de faillite de la société.
résumé non officiel
Article 1194Modifié le 26 juillet 2008
Lorsque la loi exige qu'une décision soit prise par résolution spéciale, l'assemblée générale doit statuer à une majorité d'au moins trois quarts du total des voix des actionnaires présents à l'assemblée et ayant le droit de voter.
résumé non officiel
Article 1254
En cas de dissolution d'une société de personnes ou d'une société, le liquidateur doit en demander l'enregistrement dans les quatorze jours de la dissolution, en indiquant pour enregistrement le nom de chacun des liquidateurs.
résumé non officiel
Article 1253Modifié le 26 juillet 2008
Dans les quatorze jours de la dissolution, ou de sa nomination si le tribunal l'a nommé, le liquidateur doit : (1) annoncer au public, au moins une fois dans un journal local, que la société est dissoute et inviter les créanciers à lui présenter leurs créances ; (2) adresser le même avis par lettre recommandée à chacun des créanciers figurant dans les livres, comptes ou documents de la société.
résumé non officiel
Article 1270
À la fin de la liquidation, le liquidateur établit un rapport exposant le déroulement de la liquidation et le sort des biens de la société, puis convoque l'assemblée générale pour le lui présenter et donner des explications. Une fois le rapport approuvé, il doit faire enregistrer la délibération dans les quatorze jours de l'assemblée ; cet enregistrement marque la clôture de la liquidation.
résumé non officiel
Article 1251
Lorsqu'une société de personnes ou une société est dissoute pour une cause autre que la faillite, l'associé gérant ou les administrateurs deviennent liquidateurs, sauf disposition contraire du contrat de société ou des statuts. À défaut de liquidateur, le tribunal en nomme un à la demande du ministère public ou de toute autre personne intéressée.
résumé non officiel
Article 1237Modifié le 7 février 2023
Le tribunal peut aussi dissoudre une société à responsabilité limitée : (1) faute dans le dépôt du rapport de l'assemblée constitutive ou dans sa tenue ; (2) activité non commencée dans l'année de l'enregistrement, ou suspendue une année entière ; (3) pertes seules, sans espoir de redressement ; (4) actionnaires réduits à un seul ; (5) toute autre cause empêchant sa survie. Au cas (1), il peut plutôt, s'il le juge bon, ordonner ce dépôt ou cette assemblée.
résumé non officiel
Article 72 Revenue Code
Société ou société de personnes morale dissoute: liquidateur et gérant avisent conjointement l'agent d'évaluation sous 15 jours de l'enregistrement, sinon il peut exiger une fois l'impôt dû en sus. Cette date clôt l'exercice; déclaration et paiement conjoints selon les articles 68 et 69. S'ils sont empêchés et requièrent sous 30 jours, le Directeur général peut proroger le délai et, en liquidation seulement, l'exercice. Société de personnes sans liquidation: son gérant répond avec les associés gérants.
résumé non officiel
Supreme Court decisions
- 4538/2566 (2023): A Company Struck Off the Register as Defunct Needs No Liquidation
Sources
- Civil and Commercial Code, Office of the Council of State, retrieved 31 October 2026
- Revenue Code, retrieved 4 November 2026
- deka.supremecourt.or.th, Supreme Court of Thailand decisions database (copy held in our library), retrieved 19 February 2026
Legal Requirements for Closing a Company in Thailand
The process begins with a shareholder resolution approving the dissolution. This decision must be officially recorded and reported to the Ministry of Commerce and the DBD. A liquidator must be appointed to manage the process. They will make sure all assets are distributed correctly. They will also settle debts and meet legal obligations, including those for social security.
One of the most critical steps is obtaining tax clearance from the Revenue Department. Before a company can be fully deregistered, it must submit all unpaid tax returns. It also needs to settle any remaining debts. Within fifteen days of the registration of dissolution, the liquidator and the manager must jointly notify the Revenue Department, on pain of a surcharge equal to the tax due (Revenue Code section 72); the Revenue Department’s review of the final returns is what usually controls the timetable.
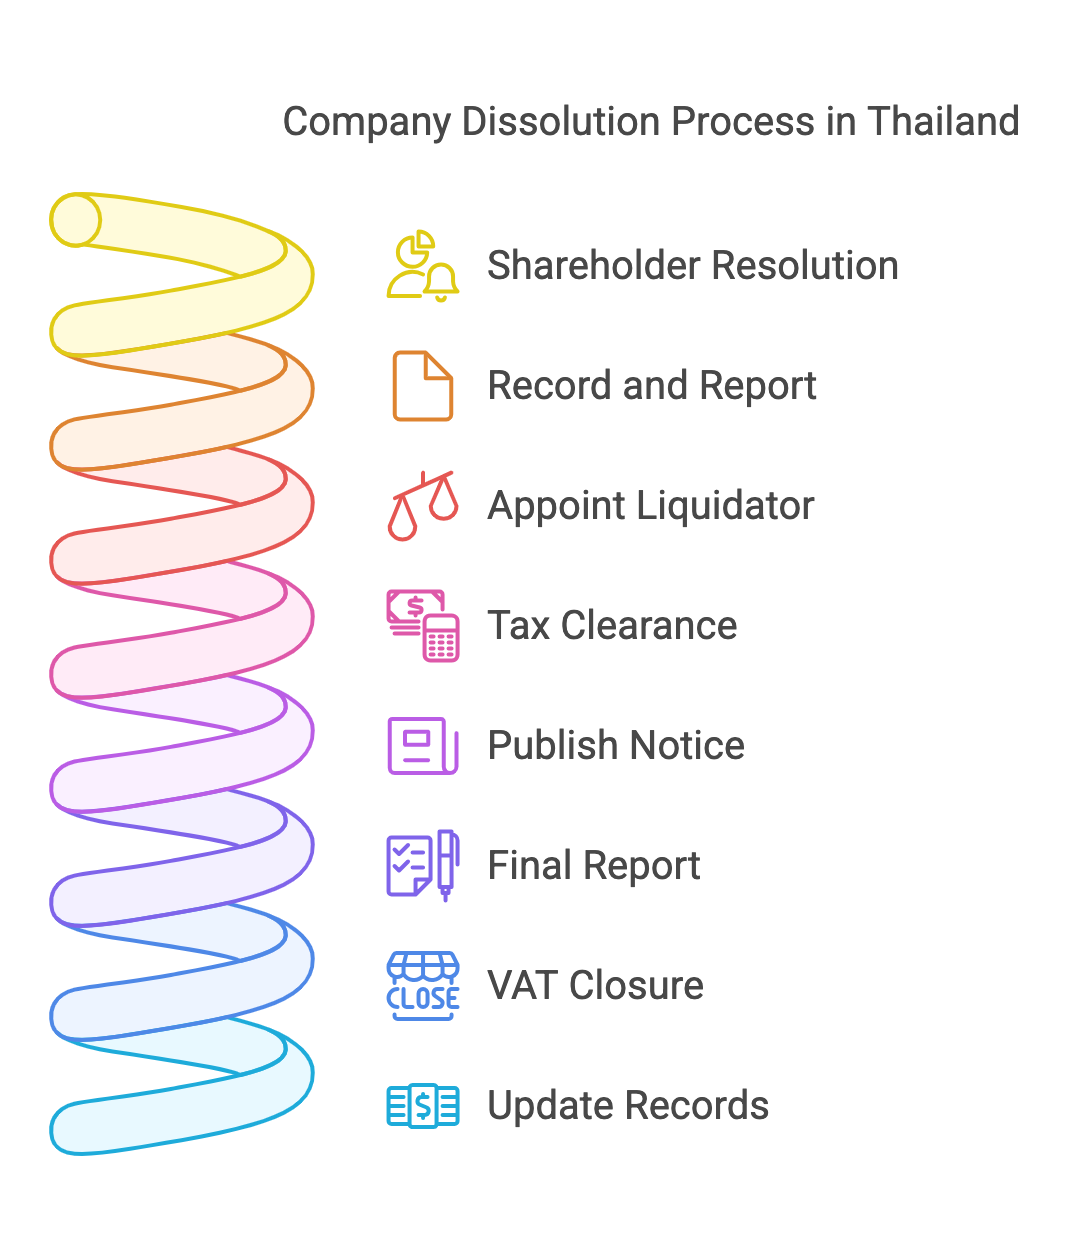
Within fourteen days of the dissolution, the liquidator must advertise it at least once in a local newspaper, calling on creditors to file their claims, and send the same notice by registered post to every creditor named in the company’s books (section 1253). Once all debts and taxes are resolved, the final liquidation report goes to a general meeting for approval and is then registered with the DBD within fourteen days, which completes the liquidation (section 1270).
If the company is registered for Value-Added Tax (VAT), it must be considered when closing a Thai company. the VAT registration must also be closed with the Revenue Department. Before doing so, all past due VAT returns must be filed and any outstanding VAT liabilities settled.
Companies must also make sure that all past financial statements and accounting records are current. This includes any missing reports from earlier years. Even if the company has not been actively trading, failure to submit required filings can delay the dissolution process. A final financial audit is usually required before obtaining tax clearance.
Step-by-Step Guide to Closing a Company in Thailand
The process starts with a formal shareholder meeting. The dissolution is a special resolution, so it needs at least three-quarters of the votes of the shareholders present and entitled to vote. This decision is then filed with the DBD, along with the appointment of a liquidator.
Once appointed, the liquidator takes over company affairs, ensuring that all financial matters, including debts and taxes, are settled. The Revenue Department plays a key role in this stage, conducting audits and verifying that all outstanding tax obligations are met before issuing a tax clearance certificate.
The public notice of dissolution comes early, within fourteen days of the dissolution, in a newspaper and by registered letter to known creditors (section 1253), so that creditors can submit their claims. After debts and taxes are settled, the liquidator distributes any remaining assets to the shareholders. This ensures that all unpaid debts are handled.
Finally, the liquidator prepares a closing report detailing the settlement of all assets and liabilities. The liquidator then calls a general meeting to approve it and, once the meeting approves it, registers the approved report with the DBD within fourteen days of the meeting (section 1270). Registration completes the liquidation. This completes the closure process.
There is no single timetable for every company closure. We provide a case-specific estimate after reviewing the company records, accounting position, outstanding liabilities and proposed work. Do not treat registration of dissolution and completion of the entire closure as the same milestone.
Challenges When Closing a Company in Thailand
Many business owners do not realize how long it takes to get tax clearance. This can be the hardest and longest part of the process. The Revenue Department looks closely at a company’s tax history. Any mistakes or unpaid taxes can delay the process for a long time.
Unresolved debts and creditor claims can also slow down the company liquidation process. Even minor compliance issues, such as missing corporate filings, can create additional hurdles. Employee pay, including severance and social security, must be fully paid to avoid legal issues after closure.
Legal Basis for the 75% Shareholder Approval Requirement
The approval requirement comes from two sections of the Civil and Commercial Code: section 1236(4), which makes a special resolution a ground of dissolution, and section 1194, which defines the majority a special resolution needs.
Section 1236 of the Civil and Commercial Code provides that a limited company is dissolved, among other causes, “when a special resolution for dissolution is passed” (section 1236(4)).
Section 1194 then requires a special resolution to be passed by a majority of not less than three-quarters of all the votes of the shareholders present at the meeting and entitled to vote. It is three-quarters of the votes in the room, not of all shareholders. Section 1178 is the quorum rule: at least two shareholders holding at least a quarter of the capital must attend.
These provisions establish the legal basis for the shareholder approval required for company dissolution.
Company closure: our service, fees and documents
Before quoting for a company closure, we review the company records, assets, debts and accounting position. Tell us whether you want to close the company completely or change its directors, shareholders or capital. These are different instructions.
An initial consultation costs 2,000 THB per hour. Further corporate work is quoted after reviewing the records. The consultation fee is not a fixed-price company-closure package. We confirm availability, the agreed work and the total payable before accepting the instruction.
Send the current company affidavit, shareholder list, latest accounts and details of outstanding filings. Identify the directors and authorised signatories, the company’s province, its assets and debts, any employees, and any current disputes. Explain your preferred completion date.
Accounting and tax filing are separate. ThaiLawOnline does not provide those services. An accountant must handle the accounting and tax-compliance work. Our written quote identifies the legal work included; do not assume accounting, tax filings or company-asset transfers are included.
We confirm the timetable after reviewing the records and proposed route. Missing accounts, unresolved liabilities and additional work identified during review affect the estimate. We do not promise a completion date before assessing the file.
Book an initial consultation, or compare our published legal fees. When booking, state “company closure” and identify the records already available.
Last reviewed: 27 September 2026. The dissolution, liquidation and striking-off statements were read in Thai against Civil and Commercial Code sections 1178, 1194, 1236, 1237, 1251, 1253, 1254, 1273/1 and 1273/2. Not verified in this review: the Revenue Department and tax-clearance practice described above, which rests on practice rather than a statutory text, and the service and fee section.
Faqs about closing a company in Thailand:
What is the process for closing a Thai company through liquidation?
To close a Thai company through liquidation, you must follow several steps. First, hold a meeting to pass a resolution to dissolve the company. Next, appoint a liquidator. Then, notify creditors. Finally, settle debts and distribute the company’s assets. Legal and accounting services in Thailand must be enlisted to ensure compliance with company law.
Q: What are the reasons a limited company in Thailand might need to close?
A limited company in Thailand may need to close for several reasons. These can include ongoing financial losses, trouble running the business, or a choice to shut down. Voluntary liquidation is often pursued when the shareholders decide that it’s no longer feasible to continue business operations.
How can outstanding debts affect the liquidation and dissolution process?
Outstanding debts must be settled before the liquidation and dissolution process can be completed. Creditors have the right to claim the assets of the company to satisfy any outstanding debts. If a company cannot pay its debts, a creditor can petition for its bankruptcy, and a bankrupt company’s assets are then collected and distributed by the Official Receiver rather than a liquidator.
What role does a liquidator play in closing a company in Thailand?
A liquidator must be appointed to wind up the affairs of the company. The liquidator’s responsibilities include collecting and liquidating the company’s assets, paying off debts, and distributing any remaining assets to the shareholders. They ensure that the company closure complies with all legal requirements.
Are there any obligations for company directors during the company closure process?
Company directors have important duties during the company closure process. They must hold a meeting to pass a resolution for dissolution and hand the company over to the liquidator, who then notifies the creditors (section 1253). Finally, they must accurately report the company’s financial affairs. Directors must also ensure compliance with Thai company law throughout the process.
What is the difference between voluntary liquidation and court-ordered liquidation?
Voluntary liquidation starts when the shareholders pass a special resolution to dissolve the company. This often happens for financial or strategic reasons. Court-ordered dissolution happens on one of the grounds in section 1237. A company that cannot pay its debts is instead taken into bankruptcy on a creditor’s petition, and the Official Receiver handles its assets.
How does closing down a business in Thailand affect company employees?
To close a business in Thailand, you must honor all employee contracts. This includes severance payments and other legal rights. A full and final release signed by each employee after the employment has ended can settle those claims; see the rules on severance pay waivers and exit releases in Thailand. Employees must be notified in advance of the company closure, and all obligations towards them must be settled before the business operations are fully terminated.
Does ThaiLawOnline’s company-closure service include accounting and tax filing?
No. We assess and quote for the agreed legal work. Accounting and tax filing must be handled by an accountant. Send your latest accounts and filing status at the outset so the legal scope and timetable reflect the work still outstanding.
How does the decision to close a business in Thailand impact its shareholders?
Closing a business in Thailand affects shareholders. It may lead to distributing any leftover assets after paying all debts. Shareholders should be part of the decision-making process. They need to vote on the resolution to dissolve the company.
What steps must be followed to officially notify the closure of a Thai company?
To officially close a Thai company, the company must inform the Department of Business Development. It must also notify other relevant authorities. All outstanding tax obligations must be settled. Finally, all creditors need to be informed. These steps are crucial for legally completing the company closure process.
Links:
Thai Law Updates, free by email
Plain-English updates on Thai law changes that affect foreigners: property, visas, marriage, business and wills. One short email a month from a firm practicing since 2006. No spam, unsubscribe anytime.