


Reviewed by Wichuda Atthamethakon, LL.M., Thai Bar Licence 3149/2556, for ThaiLawOnline, a Thai law firm acting for foreigners since 2006.
Update log
- 3 November 2026: Added the statute box with Thai, English and French text and checked the page against the official text
The Evolution of Cryptocurrency Laws in Thailand: A Timeline of Regulatory Changes and Future Implications. This is not an exhaustive list and just some of the evolution in that field.
Table of Contents
1. Introduction to the Timeline of Cryptocurrency Laws in Thailand
Last reviewed: 25 September 2026, adding the 2025 extraterritorial licensing amendment (section 26/1) below. This page is a timeline, and its narrative entries run to 2024. The tax position was re-checked against primary sources for this review: royal decrees Nos. 744 of B.E. 2565, 779 of B.E. 2566, and 788 and 789 of B.E. 2567, each read from its Royal Gazette PDF, and the Revenue Department royal decree register enumerated end to end to confirm that nothing later than No. 789 touches digital assets. The foreign-income paragraph was checked against Revenue Departmental Instructions Por. 161/2566 and Por. 162/2566. Not verified in this review: SEC and Ministry of Finance notifications made after B.E. 2563, which are not held in the sources available to us, so licensing and exchange-conduct rules stated above should be confirmed with the SEC before you rely on them. Re-checked on 5 October 2026: the Revenue Department’s ministerial regulation register was searched as well as its royal decree register, and Ministerial Regulation No. 399 (B.E. 2568) was read from its Royal Gazette image (vol. 142, part 56 Kor, 5 September 2025); the tax section and the tax FAQ now carry its 2025 to 2029 exemption for individuals’ gains through Thai-licensed operators, which the earlier statement that nothing had changed after No. 789 missed. The regulator FAQ no longer names the Bank of Thailand as a regulator under the Decree.
Cryptocurrency has changed finance, bringing new ideas and growth. But governments face challenges like protecting consumers and stopping illegal money activities. Thailand, with a growing crypto market, has made many rules over time. This article looks at the history of cryptocurrency laws in Thailand, showing important events and what might happen next. Let’s look at how the cryptocurrencies in Thailand have evolved.
2. The Early Stages: Recognizing the Potential (2014-2017)
In these early years, Thailand recognized the potential of cryptocurrencies and blockchain technology to spur economic growth. However, the absence of clear regulations created a degree of uncertainty and risk. Let’s explore Cryptocurrency Laws in Thailand per year:
2014: The Bank of Thailand issues a statement. It warns that bitcoin is not a currency and that its use carries risks. You can find an article of Coindesk about it :
2017: The UNODC Regional Office for Southeast Asia and the Pacific makes a meeting in Thailand in July. Thailand wants to Thailand strengthens capacity to trace and investigate cryptocurrencies
https://www.unodc.org/roseap/en/2017/07/cryptocurrencies/story.html
The Thai government initiates discussions to regulate and legitimize cryptocurrency exchanges, acknowledging the need for investor protection and anti-money laundering measures.
3. Establishing Regulatory Frameworks of Cryptocurrency Laws in Thailand(2018)
In 2018, Thailand took significant steps to establish comprehensive regulatory frameworks, bringing clarity and legitimacy to the cryptocurrency market. In May 2018, the Thai Ministry of Finance introduces the Emergency Decree on Digital Asset Businesses, marking the first legislation to regulate digital assets and initial coin offerings (ICOs).
Bitcoin was still seen mainly as a way for criminals to launder money. We now know that cash and conventional banking are used far more in criminal networks.
June 2018: The Securities and Exchange Commission (SEC) issues regulations for ICOs, defining required licenses and thresholds for fundraising activities. Satang was one of the first exchanges in Thailand.
https://www.sec.or.th/EN/Pages/News_Detail.aspx?SECID=8285
4. Building Trust and Security (2019-2020)
With initial regulations in place, Thailand focused on strengthening the security and trustworthiness of its cryptocurrency ecosystem. The government implemented measures to protect investors and combat illegal activities.
March 2019: The SEC approves the first four cryptocurrency exchanges, providing a much-needed framework for their operations. Exchanges are required to comply with anti-money laundering (AML) and know-your-customer (KYC) regulations. They also approved some cryptocurrencies to be traded
July 2019: The SEC grants an additional license to a cryptocurrency brokerage firm, demonstrating the government’s commitment to fostering a regulated crypto market.
5. Recent Developments and Future Implications in the Timeline of Cryptocurrency Laws in Thailand
Thailand has continued to evolve its cryptocurrency regulations, considering the global landscape and emerging technologies to ensure its policies remain effective and in line with international standards.
October 2020: The Thailand Securities and Exchange Commission proposes new regulations requiring cryptocurrency exchanges to have a minimum registered capital of ฿50 million ($1.6 million) and minimum $1 million digital asset operation fund.
January 2021: Thailand’s SEC enforces mandatory identification verification for cryptocurrency trading accounts, further strengthening AML efforts. This was really when the digital asset regulations in Thailand started.
June 2021: After the collapse of the market in May 2021, the SEC of Thailand prohibited :
- Meme token
- Fan token
- Non-fungible token (NFT)
- Digital tokens which are utilized in a blockchain transaction and issued by digital asset exchanges or related persons.
6. Foreigners can’t do KYC in Thailand parts of 2023-2024
Between July 2023 and February 2024, foreigners had trouble with crypto exchanges in Thailand refusing to let them deposit or withdraw money. We were told it was because of a new system from the anti-laundering money office.
7. Crypto hub in 2024?
In February 2024 the government announced it would change the taxes on cryptocurrencies to make Thailand a hub for crypto. A separate change, and one that is often stated too broadly: Revenue Departmental Instruction Por. 161/2566 of 15 September 2023, as qualified by Por. 162/2566 of 20 November 2023, does not tax all foreign earnings of anyone resident here. It applies to a person who is in Thailand for 180 days or more in the tax year, and it bites on foreign-source income brought into Thailand, in the year it is brought in rather than the year it is earned. Por. 162 then carves out income that arose before 1 January 2024 entirely. Money earned abroad and left abroad is not caught by it.
April 2025: the extraterritorial amendment and who now needs a Thai license
On 12 April 2025 the government published the Emergency Decree on Digital Asset Businesses (No. 2) B.E. 2568 in the Royal Gazette, and it took effect the next day. Several English-language summaries of this amendment call it a “Royal Decree.” The SEC’s own English translation of the instrument names it an Emergency Decree, the same type as the 2018 Decree it amends, so that is the title used on this page.
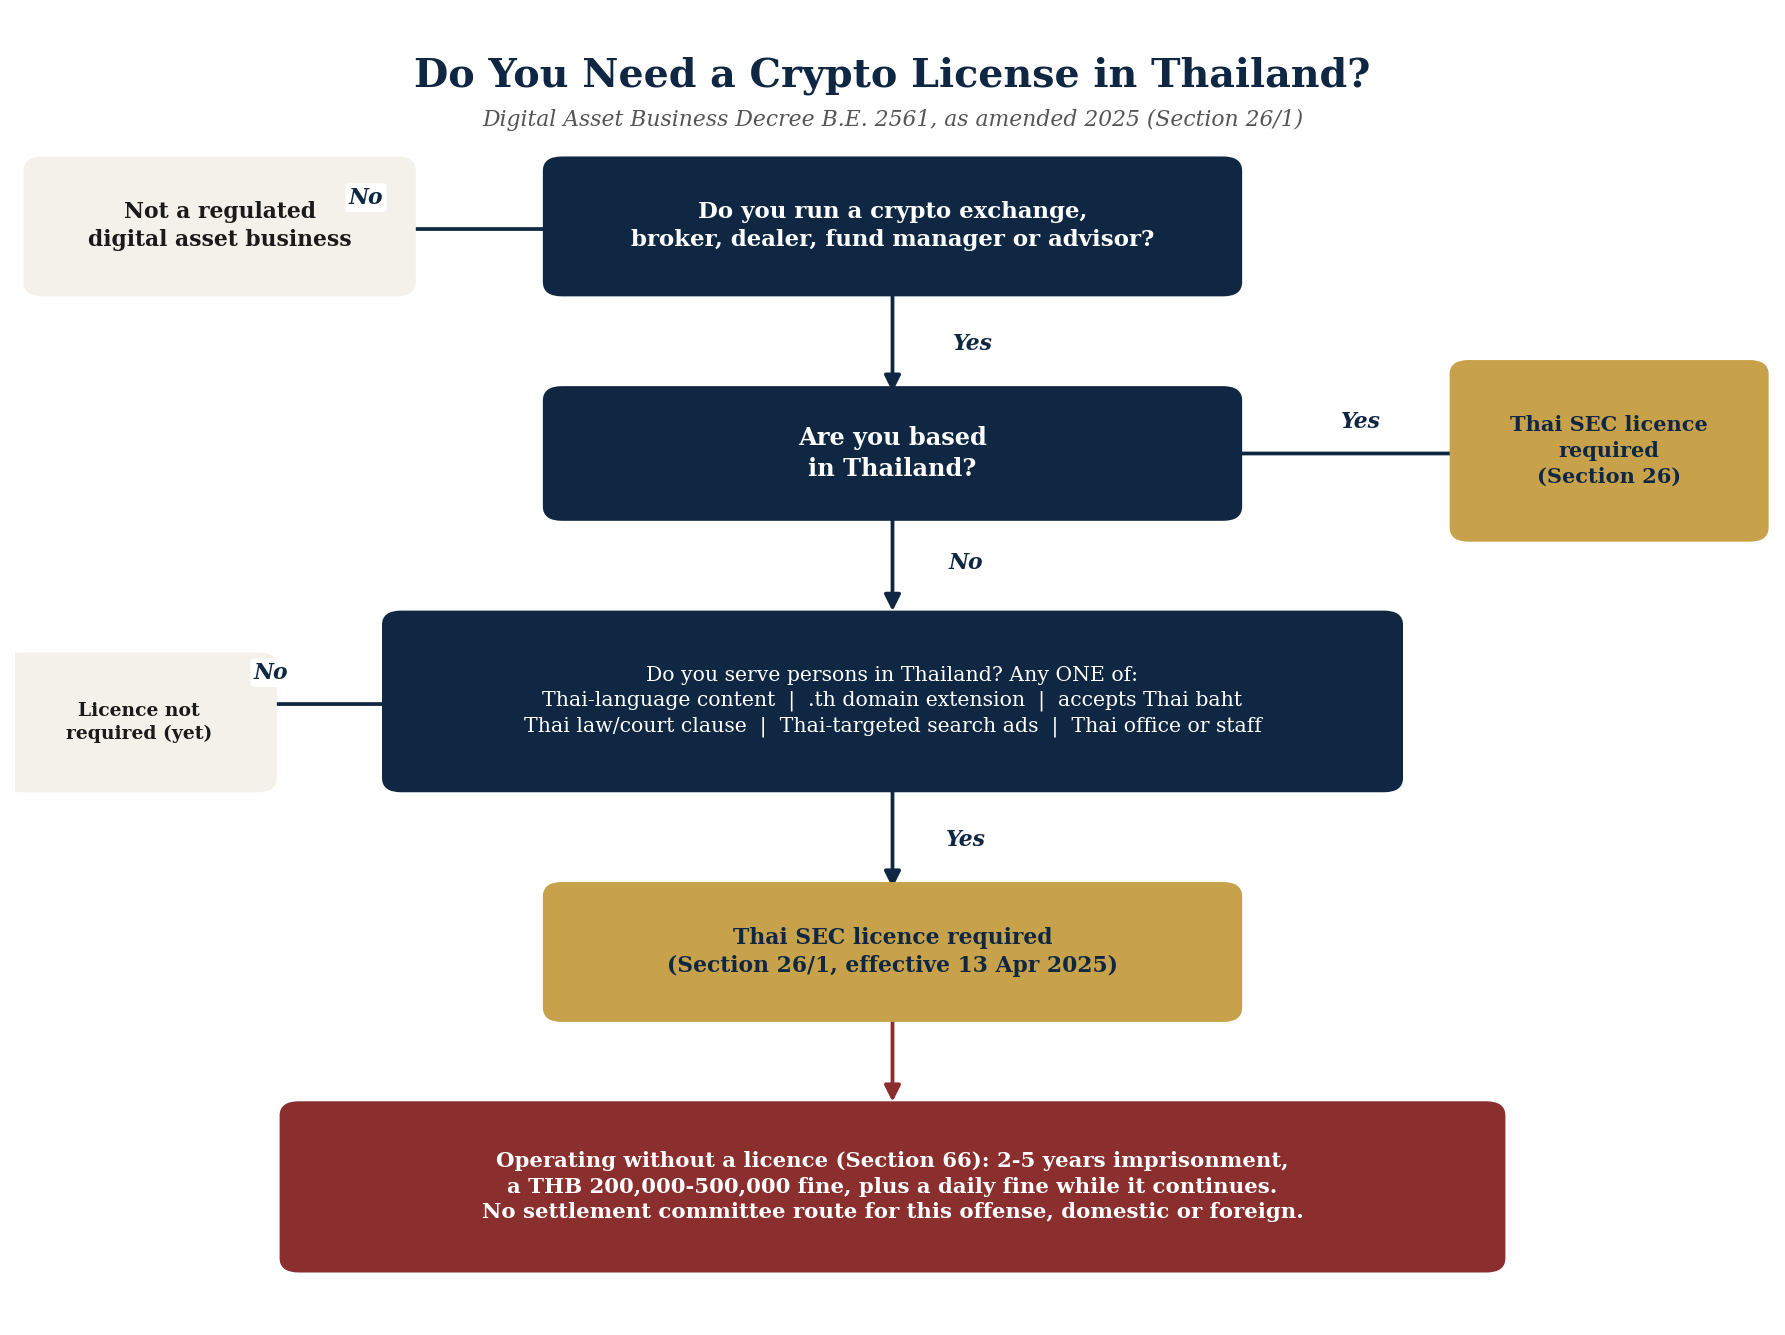
The amendment adds a third paragraph to section 26 of the Decree, which brings an operator based outside Thailand within the licensing requirement if it serves persons in Thailand, unless the service is one the SEC has exempted by notification. It also adds a new section 26/1, which deems an operator to be serving persons in Thailand if it has any ONE of the following features:
- Displays content in the Thai language
- Uses a .th domain, or a name that signals Thailand
- Accepts Thai baht, or a Thai bank or e-money account
- States that Thai law or a Thai court governs the service
- Pays for search engine placement aimed at users in Thailand
- Has an office, unit or staff, wherever located, set up to support or assist users in Thailand
- Meets any other characteristic the SEC announces
A foreign exchange with no Thai office can still be caught. An exchange that takes Thai baht deposits, shows Thai-language pages, or buys search ads that target Thailand is deemed under section 26/1 to serve persons in Thailand, and so needs a licence under section 26, the same as a Thai-based operator.
Which digital asset licence applies to you
The 2018 Decree sets out four categories of digital asset business at section 3: an exchange, a broker, a dealer, and any other business the Minister prescribes. A 2020 Ministry of Finance notification used that fourth category to add two more: a digital asset fund manager, who manages digital assets for someone else’s benefit, and a digital asset advisor, who advises on digital asset value or investment decisions outside SEC-licensed securities advice. An operator already running in these two categories in 2020 had 90 days to apply; that window closed in February 2021, so a new fund manager or advisor needs the licence before it starts, not a grace period.
Minimum paid-up capital is set by SEC Notification No. Kor Thor. 28/2567, published in the Royal Gazette (volume 141, special part 297 Ngor, pages 71 to 73) and in force since 1 November 2024. It replaced the 50 million baht figure set in 2020. An exchange that holds client assets needs 100 million baht. An exchange that does not hold client assets, a broker or dealer that does, and a custodial wallet provider need 50 million baht. A fund manager needs 25 million baht, or 10 million baht if it holds no client assets and serves institutional investors only. A broker or dealer that holds no client assets needs 10 million baht, and an advisor 1 million baht. An operator licensed in several categories needs the highest figure that applies. Operators licensed before November 2024 had to reach half of the new figure by 1 May 2025 and all of it by 1 November 2025. The 1 million US dollar operation fund in the October 2020 entry above was a proposal and is not part of this notification.
Operating without a licence: penalties and enforcement
Section 66 sets the penalty for running a digital asset business without a licence at imprisonment of 2 to 5 years and a fine of 200,000 to 500,000 baht, plus a further daily fine of up to 10,000 baht for every day the violation continues. This penalty applies equally to a domestic operator caught under section 26 and a foreign operator caught under the new section 26/1.
Some summaries describe the extraterritorial case as harsher because it cannot be settled by paying a fine. The Decree’s own settlement provision tells a simpler story: section 95 lists the specific offenses its settlement committee may compound, and section 66, unlicensed operation, has never been on that list, for a domestic operator or a foreign one. The 2025 amendment does not create a new, harsher track for foreign platforms. It extends the same licence requirement, and the same criminal exposure that has always attached to unlicensed operation, to operators outside Thailand.
The government has already used this power. The Ministry of Digital Economy and Society, under a companion 2025 amendment to the cybercrime law, can block access to an unlicensed platform without going to court first. It exercised that power on 28 June 2025 against five platforms: Bybit, CoinEx, 1000X, OKX and XT.COM. Separately, the SEC has filed criminal complaints naming OKX and CoinEx for unlicensed digital asset exchange operation, and in 2026 filed complaints against five individuals over unlicensed Worldcoin (WLD) trading. These are SEC filings and ministry blocking orders, not court judgments; no Thai court has yet ruled on section 26/1 in a published decision.
Crypto profits carry their own tax rules, separate from the licensing question above. See our guide to cryptocurrency tax in Thailand for how gains are taxed and what the current VAT exemption covers.
Assessable income is income of the following types, including the tax that the payer or another person bears on behalf of the recipient for income of those types, at whatever stage: (1) income from employment, whether salary, wages, per diem, bonus, annual allowance, gratuity, pension, house rent allowance, money calculated from the value of living in a house provided rent-free by the employer, money paid by the employer in settlement of any debt that the employee has a duty to pay, and money, property or any benefit whatsoever received by reason of employment; (2) income by reason of a duty or position of work performed or from services undertaken, whether fees, commissions, discounts, subsidies in work performed, meeting allowances, gratuities, bonuses, house rent allowance, money calculated from the value of living in a house provided rent-free by the payer, money paid by the payer in settlement of any debt that the recipient has a duty to pay, and money, property or any benefit whatsoever received by reason of that duty, position of work or services undertaken, whether the duty, position or service is regular or temporary; (3) the value of goodwill, of copyright or of other rights, annuities or income in the nature of yearly payments derived from a will, another juristic act or a court judgment; (4) income being: (a) interest on bonds, interest on deposits, interest on debentures, interest on bills, interest on loans whether secured or not, interest on loans subject to withholding of tax under the law on petroleum income tax, only as to the part remaining after withholding of tax under that law, or the difference between the redemption price and the sale price of a bill or debt instrument issued and first sold below its redemption price by a company, a juristic partnership or another juristic person, including income similar to interest, and benefits or other consideration received from lending or from claims of debt of every kind, whether secured or not; (b) dividends, shares of profit or any other benefit received from a company, a juristic partnership, or a financial institution established under a specific law of Thailand for lending to promote agriculture, commerce or industry, and dividends or shares of profit subject to withholding of tax under the law on petroleum income tax, only as to the part remaining after withholding of tax under that law. For the purpose of calculating income under paragraph one, where a legitimate child who has not yet attained majority is the income earner and the marriage of the father and mother subsisted throughout the tax year, the income of that child shall be deemed the income of the father, but if the marriage of the father and mother did not subsist throughout the tax year, the income of that child shall be deemed the income of the father or the mother exercising parental power, or of the father where the father and mother exercise parental power jointly. Paragraph two shall apply mutatis mutandis to an adopted child who has not yet attained majority and is an income earner. (c) bonuses paid to shareholders or partners in a company or juristic partnership; (d) money from a reduction of capital of a company or juristic partnership, only as to the part paid not exceeding the sum of profits and reserves; (e) money from an increase of capital of a company or juristic partnership created from profits earned or from reserves combined; (f) benefits received from the amalgamation, acquisition or dissolution of companies or juristic partnerships, valued in money in excess of capital; (g) benefits received from the transfer of a partnership interest, transfer of investment units, or transfer of shares, debentures, bonds, or bills or debt instruments issued by a company, a juristic partnership or another juristic person, including income from the sale of investment units back to a company or juristic partnership that is a mutual fund, only as to the amount valued in money in excess of the investment; (h) shares of profit or any other benefit of the same nature received from holding or possessing digital tokens; (i) benefits received from the transfer of cryptocurrency or digital tokens, only as to the amount valued in money in excess of the investment; (5) money or other benefits received by reason of: (a) the letting of property; (b) breach of a hire-purchase contract for property; (c) breach of an instalment sale contract where the seller recovers the property sold without having to return the money or benefits already received. In case (a), if the assessment official has reasonable grounds to believe that the income earner has declared income too low and not in accordance with the facts, the assessment official has the power to assess that income according to the amount for which the property could ordinarily be let, and the amount so assessed shall be deemed the assessable income of the income earner. In this case the assessment may be appealed, and the provisions on appeals in Part 2, Chapter 2, Title 2 shall apply mutatis mutandis. In cases (b) and (c), all money or benefits received from the date of the contract to the date of breach shall be deemed assessable income of the year in which the breach occurs; (6) income from a liberal profession, namely law, the healing arts, engineering, architecture, accountancy, fine arts, or another liberal profession of a type to be prescribed by royal decree; (7) income from contracting in which the contractor provides the essential materials in addition to tools; (8) income from business, commerce, agriculture, industry, transport or any other activity not specified in (1) to (7). The tax under paragraph one that the payer or another person bears on behalf of the recipient for income of any type, at whatever stage or in whatever tax year, shall be deemed income of the same type and of the same tax year as the income for which it was borne. ThaiLawOnline translation A person, partnership, company, association or body of persons paying assessable income under Section 40 shall withhold income tax each time assessable income is paid, by the following methods: (1) In the case of assessable income under Section 40 (1) and (2), multiply the assessable income paid by the number of payments to be made, to obtain an amount as if paid for the whole year, then compute the tax on the basis in Section 48. Divide the total tax so obtained by the number of payments to be made, and withhold the resulting amount as tax. If the division by the number of payments under the preceding paragraph does not come out even and leaves a remainder, add an amount equal to that remainder to the tax to be withheld at the last payment of that year, so that the total tax withheld for the whole year equals the amount of tax payable for the whole year. In the case of assessable income under Section 40 (1) and (2) that is money paid by an employer once only by reason of leaving employment, computed from the period of work and paid in accordance with the rules, procedures and conditions determined by the Director-General, compute the tax on the basis in Section 48 (5) and withhold the total tax so obtained. In the case of assessable income under Section 40 (2), other than that specified in paragraph three, paid to a recipient who is not a resident of Thailand, withhold at the rate of 15.0% of the income. (2) In the case of assessable income under Section 40 (3) and (4), withhold at the income tax rates, except: (a) in the case of assessable income under Section 40 (3) and (4), other than that specified in (b), (c), (d) and (e), paid to a recipient who is not a resident of Thailand, withhold at the rate of 15.0% of the income; (b) in the case of assessable income specified in Section 48 (3) (a) and (c), withhold at the rate of 15.0% of the income; (c) in the case of assessable income specified in Section 48 (3) (b), the issuer of the bill, the issuer of the instrument evidencing a right in debt, or the juristic person transferring the bill or instrument to a person liable to income tax under this Part shall be treated as the payer of assessable income, income tax shall be collected from the income earner at the rate of 15.0% of the income, and the tax so collected shall be treated as tax withheld; (d) in the case of assessable income under Section 40 (4) (a) not specified in (b) and (c) of this Section, if the payer is not a juristic person and pays a recipient who is a resident of Thailand, no tax need be withheld under this Section; (e) in the case of assessable income under Section 40 (4) (b), withhold at the rate of 10.0% of the income; (f) in the case of assessable income under Section 40 (4) (h) and (i), withhold at the rate of 15.0% of the income. (3) In the case of assessable income under Section 40 (5) and (6) paid to a recipient who is not a resident of Thailand, withhold at the rate of 15.0% of the income. (4) Other than in the case under (5), where the payer under this Section is the government, a government organisation, a municipality, a sanitary district or another local administrative organisation paying assessable income under Section 40 (5), (6), (7) or (8), but not including payment for the purchase of agricultural crops, to any one recipient in a total amount of 10,000 baht or more, even if the payment is divided into instalments each under 10,000 baht, withhold at the rate of 1% of the amount of assessable income, except that income from contests or competitions alone shall be withheld at the income tax rates. (5) In the case of assessable income under Section 40 (8), only where paid to a recipient who sells immovable property, withhold as follows: (a) for immovable property that is inherited or received as a gratuitous gift, compute the tax on the basis in Section 48 (4) (a) and withhold the total tax so obtained; (b) for immovable property acquired otherwise than under (a), deduct a lump-sum expense as prescribed by Royal Decree, then compute the tax on the basis in Section 48 (4) (b) and withhold the total tax so obtained. (6) In the case of a transfer of ownership or possessory rights in immovable property without consideration, the transferor shall be treated as the payer of income and shall withhold tax on the basis in (5), except in the case of a transfer to a legitimate child, not including an adopted child, where the transferor shall withhold tax at 5% of the income, only on the part exceeding 20 million baht. ThaiLawOnline translation เงินได้พึงประเมินนั้นคือ เงินได้ประเภทดังต่อไปนี้ รวมตลอดถึงเงินค่าภาษีอากรที่ผู้จ่ายเงินหรือผู้อื่นออกแทนให้สำหรับเงินได้ประเภทต่าง ๆ ดังกล่าว ไม่ว่าในทอดใด
(๑) เงินได้เนื่องจากการจ้างแรงงานไม่ว่าจะเป็นเงินเดือน ค่าจ้าง เบี้ยเลี้ยง โบนัส เบี้ยหวัด บำเหน็จ บำนาญ เงินค่าเช่าบ้าน เงินที่คำนวณได้จากมูลค่าของการได้อยู่บ้านที่นายจ้างให้อยู่โดยไม่เสียค่าเช่า เงินที่นายจ้างจ่ายชำระหนี้ใด ๆ ซึ่งลูกจ้างมีหน้าที่ต้องชำระ และเงินทรัพย์สิน หรือประโยชน์ใด ๆ บรรดาที่ได้เนื่องจากการจ้างแรงงาน
(๒) เงินได้เนื่องจากหน้าที่หรือตำแหน่งงานที่ทำหรือจากการรับทำงานให้ ไม่ว่าจะเป็นค่าธรรมเนียม ค่านายหน้า ค่าส่วนลด เงินอุดหนุนในงานที่ทำ เบี้ยประชุม บำเหน็จ โบนัส เงินค่าเช่าบ้าน เงินที่คำนวณได้จากมูลค่าของการได้อยู่บ้านที่ผู้จ่ายเงินได้ให้อยู่โดยไม่เสียค่าเช่า เงินที่ผู้จ่ายเงินได้จ่ายชำระหนี้ใด ๆ ซึ่งผู้มีเงินได้มีหน้าที่ต้องชำระและเงิน ทรัพย์สิน หรือประโยชน์ใด ๆ บรรดาที่ได้เนื่องจากหน้าที่หรือตำแหน่งงานที่ทำหรือจากการรับทำงานให้นั้น ไม่ว่าหน้าที่หรือตำแหน่งงานหรืองานที่รับทำให้นั้นจะเป็นการประจำหรือชั่วคราว
(๓) ค่าแห่งกู๊ดวิลล์ ค่าแห่งลิขสิทธิ์หรือสิทธิอย่างอื่นเงินปีหรือเงินได้มีลักษณะเป็นเงินรายปีอันได้มาจากพินัยกรรมนิติกรรมอย่างอื่น หรือคำพิพากษาของศาล
(๔) เงินได้ที่เป็น
(ก) ดอกเบี้ยพันธบัตร ดอกเบี้ยเงินฝาก ดอกเบี้ยหุ้นกู้ ดอกเบี้ยตั๋วเงิน ดอกเบี้ยเงินกู้ยืมไม่ว่าจะมีหลักประกันหรือไม่ ดอกเบี้ยเงินกู้ยืมที่อยู่ในบังคับต้องถูกหักภาษีไว้ ณ ที่จ่ายตามกฎหมายว่าด้วยภาษีเงินได้ปิโตรเลียมเฉพาะส่วนที่เหลือจากถูกหักภาษีไว้ ณ ที่จ่ายตามกฎหมายดังกล่าว หรือผลต่างระหว่างราคาไถ่ถอนกับราคาจำหน่ายตั๋วเงินหรือตราสารแสดงสิทธิในหนี้ที่บริษัทหรือห้างหุ้นส่วนนิติบุคคล หรือนิติบุคคลอื่นเป็นผู้ออกและจำหน่ายครั้งแรกในราคาต่ำกว่าราคาไถ่ถอน รวมทั้งเงินได้ที่มีลักษณะทำนองเดียวกันกับดอกเบี้ย ผลประโยชน์หรือค่าตอบแทนอื่น ๆ ที่ได้จากการให้กู้ยืมหรือจากสิทธิเรียกร้องในหนี้ทุกชนิดไม่ว่าจะมีหลักประกันหรือไม่ก็ตาม
(ข) เงินปันผล เงินส่วนแบ่งของกำไร หรือประโยชน์อื่นใดที่ได้จากบริษัทหรือห้างหุ้นส่วนนิติบุคคล หรือสถาบันการเงินที่มีกฎหมายโดยเฉพาะของประเทศไทยจัดตั้งขึ้นสำหรับให้กู้ยืมเงินเพื่อส่งเสริมเกษตรกรรม พาณิชยกรรม หรืออุตสาหกรรม เงินปันผลหรือเงินส่วนแบ่งของกำไรที่อยู่ในบังคับต้องถูกหักภาษีไว้ ณ ที่จ่าย ตามกฎหมายว่าด้วยภาษีเงินได้ปิโตรเลียมเฉพาะส่วนที่เหลือจากถูกหักภาษีไว้ ณ ที่จ่ายตามกฎหมายดังกล่าว
เพื่อประโยชน์ในการคำนวณเงินได้ตามวรรคหนึ่ง ในกรณีที่บุตรชอบด้วยกฎหมายที่ยังไม่บรรลุนิติภาวะเป็นผู้มีเงินได้ และความเป็นสามีภริยาของบิดาและมารดาได้มีอยู่ตลอดปีภาษี ให้ถือว่าเงินได้ของบุตรดังกล่าวเป็นเงินได้ของบิดา แต่ถ้าความเป็นสามีภริยาของบิดาและมารดามิได้มีอยู่ตลอดปีภาษี ให้ถือว่าเงินได้ของบุตรดังกล่าวเป็นเงินได้ของบิดาหรือของมารดาผู้ใช้อำนาจปกครอง หรือของบิดาในกรณีบิดามารดาใช้อำนาจปกครองร่วมกัน
ความในวรรคสองให้ใช้บังคับกับบุตรบุญธรรมที่ยังไม่บรรลุนิติภาวะซึ่งเป็นผู้มีเงินได้ด้วยโดยอนุโลม
(ค)
เงินโบนัสที่จ่ายแก่ผู้ถือหุ้น หรือผู้เป็นหุ้นส่วนในบริษัทหรือห้างหุ้นส่วนนิติบุคคล
(ง) เงินลดทุนของบริษัทหรือห้างหุ้นส่วนนิติบุคคลเฉพาะส่วนที่จ่ายไม่เกินกว่ากำไรและเงินที่กันไว้รวมกัน
(จ)
เงินเพิ่มทุนของบริษัทหรือห้างหุ้นส่วนนิติบุคคลซึ่งตั้งจากกำไรที่ได้มาหรือเงินที่กันไว้รวมกัน
(ฉ)
ผลประโยชน์ที่ได้จากการที่บริษัทหรือห้างหุ้นส่วนนิติบุคคล ควบเข้ากัน หรือรับช่วงกัน
หรือเลิกกัน ซึ่งตีราคาเป็นเงินได้เกินกว่าเงินทุน
(ช) ผลประโยชน์ที่ได้จากการโอนการเป็นหุ้นส่วน โอนหน่วยลงทุน หรือโอนหุ้น หุ้นกู้ พันธบัตร หรือตั๋วเงิน หรือตราสารแสดงสิทธิในหนี้ที่บริษัทหรือห้างหุ้นส่วนนิติบุคคลหรือนิติบุคคลอื่นเป็นผู้ออก รวมทั้งเงินได้จากการขายคืนหน่วยลงทุนให้แก่บริษัทหรือห้างหุ้นส่วนนิติบุคคลที่เป็นกองทุนรวม ทั้งนี้ เฉพาะซึ่งตีราคาเป็นเงินได้เกินกว่าที่ลงทุน
(ซ) เงินส่วนแบ่งของกำไร หรือผลประโยชน์อื่นใดในลักษณะเดียวกันที่ได้จากการถือหรือครอบครองโทเคนดิจิทัล
(ฌ) ผลประโยชน์ที่ได้รับจากการโอนคริปโทเคอร์เรนซีหรือโทเคนดิจิทัล ทั้งนี้ เฉพาะซึ่งตีราคาเป็นเงินได้เกินกว่าที่ลงทุน
(๕) เงินหรือประโยชน์อย่างอื่นที่ได้เนื่องจาก
(ก) การให้เช่าทรัพย์สิน
(ข)
การผิดสัญญาเช่าซื้อทรัพย์สิน
(ค) การผิดสัญญาซื้อขายเงินผ่อน
ซึ่งผู้ขายได้รับคืนทรัพย์สินที่ซื้อขายนั้นโดยไม่ต้องคืนเงินหรือประโยชน์ที่ได้รับไว้แล้ว
ในกรณี (ก)
ถ้าเจ้าพนักงานประเมินมีเหตุอันควรเชื่อว่าผู้มีเงินได้แสดงเงินได้ต่ำไปไม่ถูกต้องตามความเป็นจริง
เจ้าพนักงานประเมินมีอำนาจประเมินเงินได้นั้นตามจำนวนเงินที่ทรัพย์สินนั้นสมควรให้เช่าได้ตามปกติ
และให้ถือว่า จำนวนเงินที่ประเมินนี้เป็นเงินได้พึงประเมินของผู้มีเงินได้
ในกรณีนี้จะอุทธรณ์การประเมินก็ได้ ทั้งนี้ ให้นำบทบัญญัติว่าด้วยการอุทธรณ์ตามส่วน
๒ หมวด ๒ ลักษณะ ๒ มาใช้บังคับโดยอนุโลม
ในกรณี (ข) และ (ค)
ให้ถือว่าเงินหรือประโยชน์ที่ได้รับไว้แล้วแต่วันทำสัญญาจนถึงวันผิดสัญญาทั้งสิ้น เป็นเงินได้พึงประเมินของปีที่มีการผิดสัญญานั้น
(๖) เงินได้จากวิชาชีพอิสระ
คือวิชากฎหมาย การประกอบโรคศิลปะ วิศวกรรม สถาปัตยกรรม การบัญชี ประณีตศิลปกรรม
หรือวิชาชีพอิสระอื่นซึ่งจะได้มีพระราชกฤษฎีกากำหนดชนิดไว้
(๗) เงินได้จากการรับเหมาที่ผู้รับเหมาต้องลงทุนด้วยการจัดหาสัมภาระในส่วนสำคัญนอกจากเครื่องมือ
(๘) เงินได้จากการธุรกิจ
การพาณิชย์ การเกษตร การอุตสาหกรรม การขนส่ง หรือการอื่นนอกจากที่ระบุไว้ใน (๑)
ถึง (๗) แล้ว
เงินค่าภาษีอากรตามวรรคหนึ่ง ถ้าผู้จ่ายเงินหรือผู้อื่นออกแทนให้สำหรับเงินได้ประเภทใด ไม่ว่าทอดใด หรือในปีภาษีใดก็ตาม ให้ถือเป็นเงินได้ประเภทและของปีภาษีเดียวกันกับเงินได้ที่ออกแทนให้นั้น ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State) ให้บุคคล ห้างหุ้นส่วน บริษัท สมาคม หรือคณะบุคคลผู้จ่ายเงินได้พึงประเมินตามมาตรา ๔๐ หักภาษีเงินได้ไว้ทุกคราวที่จ่ายเงินได้พึงประเมินตามวิธีดังต่อไปนี้
(๑)
ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๑) และ (๒) ให้คูณเงินได้พึงประเมินที่จ่ายด้วยจำนวนคราวที่จะต้องจ่าย
เพื่อให้ได้จำนวนเงินเสมือนหนึ่งว่าได้จ่ายทั้งปี แล้วคำนวณภาษีตามเกณฑ์ในมาตรา ๔๘
เป็นเงินภาษีทั้งสิ้นเท่าใดให้หารด้วยจำนวนคราวที่จะต้องจ่าย
ได้ผลลัพธ์เป็นเงินเท่าใด ให้หักเป็นเงินภาษีไว้เท่านั้น
ถ้าการหารด้วยจำนวนคราวที่จะต้องจ่ายตามความในวรรคก่อนไม่ลงตัว
เหลือเศษเท่าใด
ให้เพิ่มเงินเท่าจำนวนที่เหลือเศษนั้นรวมเข้ากับเงินภาษีที่จะต้องหักไว้ครั้งสุดท้ายในปีนั้นเพื่อให้ยอดเงินภาษีที่หักรวมทั้งปีเท่ากับจำนวนภาษีที่จะต้องเสียทั้งปี
ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๑) และ (๒) ซึ่งเป็นเงินที่นายจ้างจ่ายให้ครั้งเดียวเพราะเหตุออกจากงาน ซึ่งได้คำนวณจ่ายจากระยะเวลาที่ทำงานและได้จ่ายตามหลักเกณฑ์ วิธีการ และเงื่อนไขที่อธิบดีกำหนด ให้คำนวณภาษีตามเกณฑ์ในมาตรา ๔๘ (๕) เป็นเงินภาษีทั้งสิ้นเท่าใดให้หักเป็นเงินภาษีไว้เท่านั้น
ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๒) นอกจากที่ระบุไว้ในวรรคสามที่จ่ายให้แก่ผู้รับซึ่งมิได้เป็นผู้อยู่ในประเทศไทย ให้คำนวณหักในอัตราร้อยละ ๑๕.๐ ของเงินได้
(๒) ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๓) และ (๔) ให้คำนวณหักตามอัตราภาษีเงินได้ เว้นแต่
(ก) ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๓) และ (๔) นอกจากที่ระบุไว้ใน (ข) (ค) (ง) และ (จ) ที่จ่ายให้แก่ผู้รับซึ่งมิได้เป็นผู้อยู่ในประเทศไทยให้คำนวณหักในอัตราร้อยละ ๑๕.๐ ของเงินได้
(ข) ในกรณีเงินได้พึงประเมินที่ระบุในมาตรา ๔๘ (๓) (ก) และ (ค) ให้คำนวณหักในอัตราร้อยละ ๑๕.๐ ของเงินได้
(ค) ในกรณีเงินได้พึงประเมินที่ระบุในมาตรา ๔๘ (๓) (ข) ให้ถือว่าผู้ออกตั๋วเงิน ผู้ออกตราสารแสดงสิทธิในหนี้ หรือนิติบุคคลผู้โอนตั๋วเงินหรือตราสารดังกล่าว ให้แก่ผู้มีหน้าที่เสียภาษีเงินได้ตามส่วนนี้ เป็นผู้จ่ายเงินได้พึงประเมิน และให้เรียกเก็บภาษีเงินได้จากผู้มีเงินได้ในอัตราร้อยละ ๑๕.๐ ของเงินได้และให้ถือว่าภาษีที่เรียกเก็บนั้นเป็นภาษีที่หักไว้
(ง) ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๔) (ก) ที่มิได้ระบุใน (ข) และ (ค) แห่งมาตรานี้ ถ้าผู้จ่ายเงินได้มิใช่เป็นนิติบุคคล และจ่ายให้แก่ผู้รับซึ่งเป็นผู้อยู่ในประเทศไทย ไม่ต้องหักภาษีตามมาตรานี้
(จ) ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๔) (ข) ให้คำนวณหักในอัตราร้อยละ ๑๐.๐ ของเงินได้
(ฉ) ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๔) (ซ) และ (ฌ) ให้คำนวณหักในอัตราร้อยละ ๑๕.๐ ของเงินได้
(๓) ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๕) และ (๖) ที่จ่ายให้แก่ผู้รับซึ่งมิได้เป็นผู้อยู่ในประเทศไทยให้คำนวณหักในอัตราร้อยละ ๑๕.๐ ของเงินได้
(๔) นอกจากกรณีตาม (๕) ในกรณีผู้จ่ายเงินตามมาตรานี้เป็นรัฐบาล องค์การของรัฐบาล เทศบาล สุขาภิบาล หรือองค์การบริหารราชการส่วนท้องถิ่นอื่น ซึ่งจ่ายเงินได้พึงประเมินตามมาตรา ๔๐ (๕) (๖) (๗) หรือ (๘) แต่ไม่รวมถึงการจ่ายค่าซื้อพืชผลทางการเกษตร ให้กับผู้รับรายหนึ่ง ๆ มีจำนวนรวมทั้งสิ้นตั้งแต่ ๑๐,๐๐๐ บาทขึ้นไป แม้การจ่ายนั้นจะได้แบ่งจ่ายครั้งหนึ่ง ๆ ไม่ถึง ๑๐,๐๐๐ บาทก็ดี ให้คำนวณหักในอัตราร้อยละ ๑ ของยอดเงินได้พึงประเมิน แต่เฉพาะเงินได้ในการประกวดหรือแข่งขันให้คำนวณหักตามอัตราภาษีเงินได้
(๕) ในกรณีเงินได้พึงประเมินตามมาตรา ๔๐ (๘) เฉพาะที่จ่ายให้แก่ผู้รับซึ่งขายอสังหาริมทรัพย์ ให้คำนวณหักดังต่อไปนี้
(ก) สำหรับอสังหาริมทรัพย์อันเป็นมรดกหรืออสังหาริมทรัพย์ที่ได้รับจากการให้โดยเสน่หา ให้คำนวณภาษีตามเกณฑ์ในมาตรา ๔๘ (๔) (ก) เป็นเงินภาษีทั้งสิ้นเท่าใด ให้หักเป็นเงินภาษีไว้เท่านั้น
(ข)
สำหรับอสังหาริมทรัพย์ที่ได้มาโดยทางอื่นนอกจาก (ก) ให้หักค่าใช้จ่ายเป็นการเหมาตามที่กำหนดโดยพระราชกฤษฎีกา
แล้วคำนวณภาษีตามเกณฑ์ในมาตรา ๔๘ (๔) (ข) เป็นเงินภาษีทั้งสิ้นเท่าใด
ให้หักเป็นเงินภาษีไว้เท่านั้น
(๖) ในกรณีการโอนกรรมสิทธิ์หรือสิทธิครอบครองในอสังหาริมทรัพย์โดยไม่มีค่าตอบแทน ให้ถือว่าผู้โอนเป็นผู้จ่ายเงินได้ โดยให้ผู้โอนหักภาษีตามเกณฑ์ใน (๕) เว้นแต่กรณีการโอนให้แก่บุตรชอบด้วยกฎหมายซึ่งไม่รวมถึงบุตรบุญธรรม ให้ผู้โอนหักภาษีไว้ร้อยละ ๕ ของเงินได้เฉพาะในส่วนที่เกินยี่สิบล้านบาท ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State) Définit huit catégories de revenu imposable: emploi, fonctions ou services, droits et rentes, capitaux y compris cryptomonnaies, location, professions libérales, travaux à forfait avec fournitures, commerce et autres activités. L'impôt supporté par le payeur y entre; le revenu du mineur est attribué au père ou au parent exerçant l'autorité. résumé non officiel Retenue à chaque paiement : calcul annualisé pour l'article 40 (1) et (2), 15 % notamment aux non-résidents, 10 % pour l'article 40 (4) (b), 1 % sur certains paiements publics dès 10 000 bahts ; 5 % au-delà de 20 millions pour un don immobilier à un enfant légitime. résumé non officielThe law behind this page
English
Section 40 Revenue Code
Full text
Section 50 Revenue Code
Full text
ไทย
มาตรา 40 ประมวลรัษฎากร
ข้อความเต็ม
มาตรา 50 ประมวลรัษฎากร
ข้อความเต็ม
Français
Article 40 Revenue Code
Article 50 Revenue Code
Sources
The tax position, as the royal decrees actually leave it
The tax changes trailed in February 2024 were made, and they were made by royal decree under the Revenue Code. Four decrees touch digital assets, and it is worth knowing which of them is still doing any work, because the first one has expired.
- Decree No. 744 of B.E. 2565 exempted VAT on transfers of cryptocurrency or digital tokens made on a licensed digital asset exchange, but only for transfers between 1 April 2022 and 31 December 2023. It has expired and is of historical interest only.
- Decree No. 788 of B.E. 2567 is the one in force. It exempts VAT on transfers of cryptocurrency and utility tokens made on a digital asset exchange, through a digital asset broker, by a digital asset dealer or to a dealer, from 1 January 2024, with no end date written into it. It is both wider than the decree it replaced, which reached only transfers on an exchange, and open-ended where that one was not.
- Decree No. 789 of B.E. 2567 deals with income rather than VAT. Where a person receives a share of profit from holding an investment token, and 15 per cent has already been withheld at source under section 50(2) of the Revenue Code, that profit share need not be brought into the annual income tax computation at all, for amounts received from 1 January 2024. The condition is strict: it applies only if the recipient does not reclaim or credit any part of the tax withheld. In substance the 15 per cent becomes a final tax, at the recipient’s election.
- Decree No. 779 of B.E. 2566 is aimed at issuers rather than investors. It relieves a company or juristic partnership of corporate income tax and VAT on the transfer of investment tokens offered to the public, retroactively to 14 May 2018, which is the day the Emergency Decree itself came into force.
No later royal decree has changed any of this. The Revenue Department’s own royal decree register runs to No. 810 of B.E. 2569 (checked 19 October 2026), and reading it end to end, 682 decrees from No. 9 to No. 810, the last one whose subject touches digital assets is No. 789.
But the income tax on gains has changed, by ministerial regulation, which is a separate register. Ministerial Regulation No. 399 (B.E. 2568), signed on 27 August 2025 and published in the Royal Gazette on 5 September 2025 (volume 142, part 56 Kor), adds item (109) to clause 2 of Ministerial Regulation No. 126: the gain an individual makes on transferring cryptocurrency or a digital token is exempt from personal income tax where the transfer is made on a digital asset exchange, through a digital asset broker, or to a digital asset dealer licensed under the Thai digital asset law, for income received from 1 January 2025 to 31 December 2029. The exemption is limited in three ways: it is a personal income tax exemption, so it does not help a company; it covers only transfers through a Thai-licensed operator, so a gain made on a foreign platform remains assessable income; and it ends with 2029 unless extended.
Future Implications and Conclusion
Thailand is working on creating laws for cryptocurrency to make transactions safe. They want to protect investors and encourage growth and innovation. By following global standards, Thailand is becoming a good place for cryptocurrency businesses and investments. They recently made significant agreements that could see Thailand as a technological hub for the future. Crypto currency is a part of it. Microsoft announced in May 2024 a new data center in Thailand for AI and others.
It is clear that Thailand is keen to benefit from the potential of cryptocurrencies and blockchain technology while ensuring compliance with regulatory requirements. The precise future implications are yet to be seen, but with a forward-thinking approach and continuous adaptation, Thailand may well establish itself as a leading jurisdiction for the crypto industry.
Frequently Asked Questions
Is cryptocurrency legal in Thailand?
Yes. Cryptocurrency is legal to hold and trade through SEC-licensed Thai exchanges, but it is not legal tender and using it to pay for goods and services is restricted.
Who regulates cryptocurrency in Thailand?
The Securities and Exchange Commission (SEC) licenses and supervises digital asset businesses under the Emergency Decree on Digital Asset Businesses B.E. 2561 (2018), which the Minister of Finance administers. The Bank of Thailand’s role is separate and concerns payments, including the restrictions on using digital assets to pay for goods and services.
Do I have to pay tax on crypto profits in Thailand?
It depends on where you trade. Gains are assessable income in principle, but Ministerial Regulation No. 399 (B.E. 2568) exempts an individual from personal income tax on gains from transferring cryptocurrency or digital tokens on a Thai-licensed exchange, or through a licensed broker or to a licensed dealer, for income received from 1 January 2025 to 31 December 2029. Gains made on a foreign platform, and gains made by a company, are not covered.
Can I pay for goods with crypto in Thailand?
Using crypto as a means of payment is restricted and has been discouraged by regulators, so it is mainly treated as an investment asset rather than money.
Can foreign crypto exchanges serve customers in Thailand?
Only if it holds a Thai SEC licence. Since April 2025, a foreign exchange counts as serving Thai customers under section 26/1 if it uses Thai language, accepts Thai baht, or meets any of the other listed triggers, and the government has already blocked several platforms that operated without one.
Do I need a licence to trade crypto for myself?
No. Sections 26 and 26/1 regulate the businesses that run an exchange, brokerage, dealing, fund management or advisory service, not an individual who buys and holds digital assets through a licensed exchange.
What is the penalty for running an unlicensed crypto exchange in Thailand?
Section 66 sets imprisonment of 2 to 5 years and a fine of 200,000 to 500,000 baht, plus a daily fine while the violation continues. This offense cannot be settled by paying a fine through the Digital Asset Business settlement committee.
Thai Law Updates, free by email
Plain-English updates on Thai law changes that affect foreigners: property, visas, marriage, business and wills. One short email a month from a firm practicing since 2006. No spam, unsubscribe anytime.