


Évalué par Wichuda Atthamethakon, LL.M., titulaire de la licence de l’Ordre des avocats thaïlandais 3149/2556, pour ThaiLawOnline, un cabinet d’avocats thaïlandais œuvrant pour des étrangers depuis 2006.
Journal des mises à jour
- 4 novembre 2026: Added the statute box with Thai, English and French text and checked the page against the official text
Dernière révision : 26 septembre 2026. Lire en thaïlandais contre article 1686 du Code civil et commercial; L’article 2, les articles 3, 12, 16 et 17 de la loi sur l’impôt sur les successions B.E. 2558 ; les instructions du Département des recettes Por.161/2566 et Por.162/2566 ; les seuils de taxe sur les dons, qui proviennent du Code des impôts, de la loi sur le trust pour les transactions sur le marché financier B.E. 2550 et des lois des juridictions étrangères citées. Vérifié à nouveau le 5 octobre 2026 : les seuils de taxe sur les dons, qui figurent dans le Code des impôts consolidé par l’amendement n° 54 (articles 42(27), 42(28), 48(6) et 48(7)), ainsi que les articles 3, 16 et 17 de la loi sur l’impôt sur les successions, sont réécrits ; les chiffres restent les mêmes et le pourcentage de 5 % sur le montant excédentaire est désormais décrit comme une option du bénéficiaire. Vérifié à nouveau le 10 octobre 2026 : la loi sur le trust pour les transactions sur le marché financier B.E. 2550, articles 3, 8, 11 et 12, rédigés en thaïlandais dans le registre central des lois du gouvernement ; la description de la page correspond, et la règle 12 qui stipule que seule une personne morale peut créer un tel trust a été ajoutée. La législation des juridictions étrangères citées reste non vérifiée.
Pour les expatriés en Thaïlande ayant des actifs dans plus d'un pays, la planification de la succession La planification devient complexe. Les trusts sont courants au Royaume-Uni, aux États-Unis, au Canada et en Australie. La Thaïlande suit le droit civil et traite la protection des patrimoines et la succession différemment. Le droit thaïlandais ne reconnaît aucune valeur fiduciaire à moins que la loi l’autorise, et la seule loi de ce type concerne les trusts immobiliers, et non les patrimoines familiaux.
Puisque la Thaïlande ne reconnait pas les trusts nationaux, un testament fait office d'alternative : consultez notre guide sur le droit des successions en Thaïlande.
En common law, une fiducie dissocie la propriété légale de l'intérêt bénéficiaire. En tant que constituant, vous transférez des biens à un fiduciaire. Ce dernier en détient la propriété légale et gère ces biens pour vos bénéficiaires.
La Thaïlande ne reconnaît pas les trusts privés pour la planification patrimoniale familiale. Une petite exception s’applique aux trusts du marché des capitaux. Cette situation est régie par la loi sur les trusts du marché des capitaux B.E. 2550 (2007). Cette loi est supervisée par la SEC. Ce régime ne concerne pas les patrimoines personnels mais les fonds immobiliers et la titrisation : en vertu de l’article 12 de cette loi, seule une personne morale peut créer un tel trust (une société émettant des titres, le vendeur d’actifs dans une titrisation ou une autre personne morale que la SEC qualifie), donc un particulier ne peut pas l’utiliser pour conserver des patrimoines familiaux.
Table des matières
Qu'est-ce qu'une fiducie ?
Une fiducie est un arrangement juridique qui distingue la propriété légale d'un bien de ses bénéficiaires. Le constituant transfère les biens au fiduciaire, qui en détient la propriété et les gère pour le compte des bénéficiaires.
Types courants de fiducies
- fiducies révocables: Le constituant peut modifier le trust ou y mettre fin de son vivant. Ces trusts sont souvent utilisés pour faciliter la transmission du patrimoine et éviter la procédure d’homologation successorale.
- Fiducies irrévocablesPlus difficiles à modifier. Elles peuvent offrir une meilleure protection des actifs et d'éventuels avantages fiscaux.
- fiducies discrétionnairesLe fiduciaire dispose d'une certaine latitude quant à la manière et au moment de distribuer les actifs.
- Les fiducies familiales permettent de gérer le patrimoine transfrontalier et de soutenir les bénéficiaires sur plusieurs générations. Ils sont conçus pour soutenir les membres d'une famille sur plusieurs générations et contribuer à préserver le patrimoine familial, notamment pour les expatriés.
Principaux Avantages des fiducies
- Protection des actifsLes fiducies peuvent protéger les actifs contre certaines réclamations, notamment pour les expatriés confrontés au droit fiscal.
- efficacité de la planification successoraleLes fiducies permettent d'éviter l'homologation et de préserver la confidentialité de vos affaires.
- Planification successoraleLes biens peuvent se transmettre sans difficulté d'une génération à l'autre.
- planification fiscaleLes fiducies peuvent offrir des avantages fiscaux, selon la juridiction.
Les trusts en Thaïlande : situation juridique
Le système de droit civil thaïlandais exige des règles écrites claires pour les concepts juridiques. Le Code civil et commercial ne se contente pas d’omettre les trusts : l’article 1686 dispose qu’un trust créé directement ou indirectement par testament ou par tout autre acte juridique, prenant effet du vivant ou au décès, est sans effet s’il n’est pas créé en vertu d’une loi autorisant les trusts. En d’autres termes, la Thaïlande ne reconnaît pas les trusts privés pour la planification successorale personnelle en vertu du Code civil et commercial. La seule exception concerne la loi B.E. 2550 (2007) relative aux trusts pour les transactions sur le marché des capitaux. Cette loi s’applique aux activités liées aux marchés financiers réglementées par la SEC. Elle ne s’applique pas à la planification familiale ou successorale.
Des discussions ont eu lieu concernant une réforme. Dans la pratique, la situation est simple : pour créer une fiducie, il faut l’établir dans un autre pays. Limitez la fiducie étrangère aux actifs non thaïlandais. Utilisez des instruments juridiques thaïlandais pour les actifs situés en Thaïlande.
Les fiducies utilisées pour les successions familiales thaïlandaises sont donc constituées à l'étranger et ne doivent détenir que des actifs non thaïlandais. Il est fortement déconseillé de placer des biens immobiliers thaïlandais sous une fiducie étrangère. Le droit thaïlandais ne prévoit aucun mécanisme d'enregistrement du titre de propriété du fiduciaire à cette fin. Utilisez des instruments juridiques thaïlandais pour les actifs situés en Thaïlande.
Bien que la loi soit la même dans toute la Thaïlande, son application peut varier selon les districts ou les provinces. Cela peut impacter les procédures successorales ou la vérification des documents. Une planification rigoureuse permet de réduire les délais.
Le droit applicable à cette page
English
Section 1686
Full text
A trust created, whether directly or indirectly, by will or by any juristic act taking effect during lifetime or after death, has no effect, except by virtue of the provisions of a law enacted for the creation of trusts.
ThaiLawOnline translation
Section 37 Act on Conflict of Laws B.E. 2481
Full text
Succession, so far as it relates to immovable property, is governed by the law of the place where the property is situated.
ThaiLawOnline translation
Section 38 Act on Conflict of Laws B.E. 2481
Full text
As regards movable property, succession by statutory right or by will is governed by the law of the domicile of the deceased at the time of death.
ThaiLawOnline translation
Section 42 Revenue Code
Full text
The following types of assessable income shall be exempt and need not be included in the computation for income tax: (1) per diem allowances or travel expenses which an employee, or a person holding a duty or position, or a person performing work, has spent in good faith as necessary exclusively for the performance of his or her duties and has spent entirely for that purpose; (2) travel expenses and travelling per diem allowances at the rates fixed by the government under the Royal Decree on rates of travel expenses and travelling per diem allowances; (3) travelling money paid by an employer to an employee, only the portion which the employee has spent entirely as necessary for travelling from another locality to take up employment for the first time, or for returning to the place of origin when the employment has ended; but this exemption does not include travelling money received by the employee for returning to the place of origin and for taking up employment with the former employer within three hundred and sixty-five days from the date on which the previous employment ended; (4) where an employer and an employee entered into a contract in good faith before the Income Tax Act B.E. 2475 came into force, containing a provision that the employer would pay a gratuity, fee, commission or bonus to the employee in a lump sum when the employment ended, even if the full amount is paid after the provisions of this Part come into force, the part of the gratuity, fee, commission or bonus that is wages for work done before the Income Tax Act B.E. 2475 came into force need not be included in the computation for income tax; (5) special position allowances and housing allowances, or houses provided rent-free, for government officials of Thai embassies or consulates abroad; (6) income from the sale of, or discounts on the purchase of, government duty stamps or postage stamps; (7) meeting allowances for commission or committee members, or teaching fees and examination fees, paid by the government or a government educational institution; (8) the following interest: (a) interest on Government Savings Bank lottery bonds, or interest on Government Savings Bank deposits of the demand deposit type only; (b) interest on savings deposits received from a cooperative; (c) interest on savings deposits with banks in the Kingdom repayable on demand, only where the income earner receives such interest in a total amount not exceeding ten thousand baht throughout that tax year, in accordance with the rules, procedures and conditions prescribed by notification of the Director-General; (9) the sale of movable property that is inheritance, or of movable property acquired not for the purpose of trade or profit, but not including ships, vessels of six tons gross or more, steamships or motor vessels of five tons gross or more, or rafts; (10) income received from inheritance; (11) awards for education or scientific research, prizes from government lotteries or Government Savings Bank lottery bonds, prizes paid by the government in contests or competitions where the recipient is not a professional contestant or competitor, or rewards paid by the government for the purpose of suppressing offences; (12) special pensions, special gratuities, inherited pensions or inherited gratuities; (13) compensation for wrongful acts, money received from insurance or from funeral welfare schemes; (14) (repealed); (15) income of a farmer from the sale of rice produced by farming carried out by the farmer and/or his or her family; (16) income received from an estate which is subject to tax under section 57 bis; (17) income exempted as prescribed by Ministerial Regulation; (18) prizes from Thai Red Cross lotteries, and income from the sale of, or discounts on the purchase of, Thai Red Cross lottery tickets; (19) interest received under section 4 decies; (20) (repealed); (21) (repealed); (22) (repealed); (23) (repealed); (24) (repealed); (25) benefits received by an insured person from the Social Security Fund under the law on social security; (26) income from the transfer, without consideration, of ownership or possessory rights in immovable property to a legitimate child, not including an adopted child, only income from transfers to such legitimate child in the portion not exceeding twenty million baht per child throughout that tax year; (27) income received as maintenance or as a gift from an ascendant, descendant or spouse, only the portion not exceeding twenty million baht throughout that tax year; (28) income received as maintenance out of moral duty, or as a gift on the occasion of a ceremony or in accordance with custom and tradition, from a person who is not an ascendant, descendant or spouse, only the portion not exceeding ten million baht throughout that tax year; (29) income received as a gift where the donor declares an intention, or it is evident that the donor intends, that it be used for religious, educational or public-benefit purposes, in accordance with the rules and conditions prescribed in Ministerial Regulations.
ThaiLawOnline translation
Section 48 Revenue Code
Full text
Assessable income is subject to income tax as follows: (1) assessable income, after deductions under section 42 bis to section 47 or section 57 quinquies, leaves a balance that is net income, which is taxable at the rates in the income tax rate schedule at the end of this Chapter; (2) for a person with assessable income of 120,000 baht or more, the tax calculated under (1) shall be not less than 0.5 percent of the total assessable income. In counting assessable income under (2), assessable income under section 40 (1) is excluded; (3) an income earner may elect to pay tax at the rate of 15.0 percent of the income, without including it in the calculation of tax under (1) and (2), for the following income under section 40 (4) (a) and (g): (a) interest on bonds, interest on bank deposits in the Kingdom, interest on cooperative deposits, interest on debentures, interest on bills received from a company, a juristic partnership or another juristic person, interest on loans received from a company, a juristic partnership or another juristic person, and interest received from a financial institution established under a specific law of Thailand for lending to promote agriculture, commerce or industry; (b) the difference between the redemption price and the sale price of a bill or debt instrument issued by a company, a juristic partnership or another juristic person; (c) benefits received from the transfer of bonds, debentures, or bills or debt instruments issued by a company, a juristic partnership or another juristic person, only as to the amount valued in money in excess of the investment. An income earner who is a resident of Thailand may elect to pay tax at the rate of 10.0 percent of the income, without including it in the calculation of tax under (1) and (2), for income under section 40 (4) (b) received from a company or juristic partnership established under Thai law, or from a financial institution established under a specific law of Thailand for lending to promote agriculture, commerce or industry; (4) an income earner may elect to pay tax without including it in the calculation of tax under (1) and (2), only for income under section 40 (8) received from the sale of inherited immovable property or immovable property acquired without the object of trade or profit, as follows: (a) for income from the sale of inherited immovable property or immovable property received by gift, an expense of 50 percent of the income shall be deducted, the balance being net income, which is divided by the number of years of holding; tax is calculated on the result at the income tax rates, and the amount obtained is multiplied by the number of years of holding, the result being the tax payable; (b) for income from the sale of immovable property acquired other than under (a), expenses may be deducted as prescribed by royal decree, the balance being net income, which is divided by the number of years of holding; tax is calculated on the result at the income tax rates, and the amount obtained is multiplied by the number of years of holding, the result being the tax payable. Where tax is paid without inclusion in the calculation of tax under (1) and (2), the tax calculated shall not exceed 20 percent of the sale price. Where tax is paid with inclusion in the calculation of tax under (1) and (2), an expense of 50 percent of the income under (a), or as prescribed by royal decree under (b), as the case may be, shall be deducted, and the balance shall be included in the calculation of tax with other income. The term “number of years of holding” in (a) or (b) means the number of years counted from the year in which ownership or the right of possession of the immovable property was acquired to the year in which ownership or the right of possession of that immovable property is transferred; if it exceeds 10 years it shall be counted as 10 years only, and a fraction of a year shall be counted as 1 year; (4/1) an income earner may elect to pay tax at the rate of 5 percent of the income in excess of 20,000,000 baht, without including it in the calculation of tax under (1) and (2), for income under section 40 (8) from the transfer of ownership or the right of possession of immovable property without consideration to a legitimate child, excluding an adopted child, that is not exempt under section 42 (26); (5) an income earner may elect to pay tax without including it in the calculation of tax under (1) and (2), for assessable income under section 40 (1) and (2) that is money paid once by an employer by reason of leaving employment, calculated from the period of work and paid in accordance with the rules, procedures and conditions prescribed by the Director-General, by deducting from that assessable income an expense equal to 7,000 baht multiplied by the number of years of work, but not exceeding the assessable income, then deducting a further expense of 50 percent of the balance, and calculating the tax at the income tax rates. Where that assessable income is paid partly as a gratuity and partly as a pension, only the money paid as a gratuity shall be deemed money paid once by an employer by reason of leaving employment, and the expense of 7,000 baht shall be reduced to 3,500 baht. As to the number of years of work under paragraph one, in the case of a gratuity or any other money of the same nature paid by the government, the number of years used as the basis for calculating the gratuity or other money of the same nature under the laws, rules or regulations of the government shall be used. In calculating the number of years of work, other than in the case under paragraph three, a fraction of a year of 183 days or more shall be counted as 1 year, and a fraction of less than 183 days shall be disregarded; (6) an income earner may elect to pay tax at the rate of 5 percent of the income in excess of 20,000,000 baht, without including it in the calculation of tax under (1) and (2), for income under section 40 (8) received as support or by gift from an ascendant, a descendant or a spouse, that is not exempt under section 42 (27); (7) an income earner may elect to pay tax at the rate of 5 percent of the income in excess of 10,000,000 baht, without including it in the calculation of tax under (1) and (2), for income under section 40 (8) received as support under a moral duty or by gift on the occasion of a ceremony or in accordance with custom and tradition, from a person who is not an ascendant, a descendant or a spouse, that is not exempt under section 42 (28).
ThaiLawOnline translation
ไทย
มาตรา 1686
ข้อความเต็ม
อันว่าทรัสต์นั้น จะก่อตั้งขึ้นโดยตรงหรือโดยทางอ้อมด้วยพินัยกรรมหรือด้วยนิติกรรมใด ๆ ที่มีผลในระหว่างชีวิตก็ดีหรือเมื่อตายแล้วก็ดี หามีผลไม่ เว้นแต่โดยอาศัยอำนาจตามบทบัญญัติแห่งกฎหมายเพื่อการก่อตั้งทรัสต์เท่านั้น
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 37 พระราชบัญญัติว่าด้วยการขัดกันแห่งกฎหมาย พุทธศักราช 2481
ข้อความเต็ม
มรดกเท่าที่เกี่ยวกับอสังหาริมทรัพย์ ให้เป็นไปตามกฎหมายแห่งถิ่นที่ทรัพย์สินนั้นตั้งอยู่
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 38 พระราชบัญญัติว่าด้วยการขัดกันแห่งกฎหมาย พุทธศักราช 2481
ข้อความเต็ม
ในส่วนที่เกี่ยวกับสังหาริมทรัพย์ มรดกโดยสิทธิโดยธรรม หรือโดยพินัยกรรม ให้เป็นไปตามกฎหมายภูมิลำเนาของเจ้ามรดกในขณะที่เจ้ามรดกถึงแก่ความตาย
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 42 ประมวลรัษฎากร
ข้อความเต็ม
เงินได้พึงประเมินประเภทต่อไปนี้ ให้ได้รับยกเว้นไม่ต้องรวมคำนวณเพื่อเสียภาษีเงินได้ (๑) ค่าเบี้ยเลี้ยง หรือค่าพาหนะ ซึ่งลูกจ้าง หรือผู้รับหน้าที่หรือตำแหน่งงาน หรือผู้รับทำงานให้ได้จ่ายไปโดยสุจริตตามความจำเป็นเฉพาะในการที่ต้องปฏิบัติการตามหน้าที่ของตน และได้จ่ายไปทั้งหมดในการนั้น (๒) ค่าพาหนะและเบี้ยเลี้ยงเดินทางตามอัตราที่รัฐบาลกำหนดไว้โดยพระราชกฤษฎีกาว่าด้วยอัตราค่าพาหนะและเบี้ยเลี้ยงเดินทาง (๓) เงินค่าเดินทางซึ่งนายจ้างจ่ายให้ลูกจ้าง เฉพาะส่วนที่ลูกจ้างได้จ่ายทั้งหมดโดยจำเป็นเพื่อการเดินทางจากต่างถิ่นในการเข้ารับงานเป็นครั้งแรก หรือในการกลับถิ่นเดิมเมื่อการจ้างได้สิ้นสุดลงแล้ว แต่ข้อยกเว้นนี้มิให้รวมถึงเงินค่าเดินทางที่ลูกจ้างได้รับในการกลับถิ่นเดิมและในการเข้ารับงานของนายจ้างเดิมภายในสามร้อยหกสิบห้าวัน นับแต่วันที่การจ้างครั้งก่อนได้สิ้นสุดลง (๔) ในกรณีที่นายจ้างและลูกจ้างได้ทำสัญญากันโดยสุจริตก่อนใช้พระราชบัญญัติภาษีเงินได้ พุทธศักราช ๒๔๗๕ มีข้อกำหนดว่า นายจ้างจะชำระเงินบำเหน็จ เงินค่าธรรมเนียม เงินค่านายหน้า หรือเงินโบนัส ให้แก่ลูกจ้างเป็นจำนวนเดียวเมื่อการงานที่จ้างได้สิ้นสุดลงแล้ว แม้เงินเต็มจำนวนนั้นจะได้ชำระภายหลังที่ใช้บทบัญญัติในส่วนนี้ก็ดี เงินบำเหน็จ เงินค่าธรรมเนียม เงินค่านายหน้า หรือเงินโบนัส ส่วนที่เป็นค่าจ้างแรงงานอันได้ทำในเวลาก่อนใช้พระราชบัญญัติภาษีเงินได้ พุทธศักราช ๒๔๗๕ นั้น ไม่ต้องรวมคำนวณเพื่อเสียภาษีเงินได้ (๕) เงินเพิ่มพิเศษประจำตำแหน่ง และเงินค่าเช่าบ้าน หรือบ้านที่ให้อยู่โดยไม่ต้องเสียค่าเช่า สำหรับข้าราชการ สถานทูต หรือสถานกงสุลไทยในต่างประเทศ (๖) เงินได้จากการขาย หรือส่วนลดจากการซื้ออากรแสตมป์ หรือแสตมป์ไปรษณียากรของรัฐบาล (๗) เบี้ยประชุมกรรมาธิการหรือกรรมการ หรือค่าสอน ค่าสอบ ที่ทางราชการหรือสถานศึกษาของทางราชการจ่ายให้ (๘) ดอกเบี้ยดังต่อไปนี้ (ก) ดอกเบี้ยสลากออกสิน หรือดอกเบี้ยเงินฝากออมสินของรัฐบาลเฉพาะประเภทฝากเผื่อเรียก (ข) ดอกเบี้ยเงินฝากประเภทออมทรัพย์ที่ได้รับจากสหกรณ์ (ค) ดอกเบี้ยเงินฝากธนาคารในราชอาณาจักรที่ต้องจ่ายคืน เมื่อทวงถามประเภทออมทรัพย์ เฉพาะกรณีที่ผู้มีเงินได้ได้รับดอกเบี้ยดังกล่าวในจำนวนรวมกันทั้งสิ้นไม่เกินหนึ่งหมื่นบาทตลอดปีภาษีนั้น ทั้งนี้ ตามหลักเกณฑ์ วิธีการและเงื่อนไขที่อธิบดีประกาศกำหนด (๙) การขายสังหาริมทรัพย์อันเป็นมรดก หรือสังหาริมทรัพย์ที่ได้มาโดยมิได้มุ่งในทางการค้าหรือหากำไร แต่ไม่รวมถึงเรือกำปั่น เรือที่มีระวางตั้งแต่หกตันขึ้นไป เรือกลไฟหรือเรือยนต์ที่มีระวางตั้งแต่ห้าตันขึ้นไปหรือแพ (๑๐) เงินได้ที่ได้รับจากการรับมรดก (๑๑) รางวัลเพื่อการศึกษาหรือค้นคว้าในวิทยาการ รางวัลสลากกินแบ่งหรือสลากออมสินของรัฐบาล รางวัลที่ทางราชการจ่ายให้ในการประกวดหรือแข่งขันซึ่งผู้รับมิได้มีอาชีพในการประกวดหรือแข่งขัน หรือสินบนรางวัลที่ทางราชการจ่ายให้เพื่อประโยชน์ในการปราบปรามการกระทำความผิด (๑๒) บำนาญพิเศษ บำเหน็จพิเศษ บำนาญตกทอด หรือบำเหน็จตกทอด (๑๓) ค่าสินไหมทดแทนเพื่อละเมิด เงินที่ได้จากการประกันภัย หรือการฌาปนกิจสงเคราะห์ (๑๔) (ยกเลิก) (๑๕) เงินได้ของชาวนาที่ได้จากการขายข้าวอันเกิดจากกสิกรรมที่ตนและหรือครอบครัวได้ทำเอง (๑๖) เงินได้ที่ได้รับจากกองมรดกซึ่งต้องเสียภาษีตามความในมาตรา ๕๗ ทวิ (๑๗) เงินได้ตามที่จะได้กำหนดยกเว้นโดยกฎกระทรวง (๑๘) รางวัลสลากบำรุงกาชาดไทย เงินได้จากการขายหรือส่วนลดจากการซื้อสลากบำรุงกาชาดไทย (๑๙) ดอกเบี้ยที่ได้รับตามมาตรา ๔ ทศ (๒๐) (ยกเลิก) (๒๑) (ยกเลิก) (๒๒) (ยกเลิก) (๒๓) (ยกเลิก) (๒๔) (ยกเลิก) (๒๕) เงินประโยชน์ทดแทนที่ผู้ประกันตนได้รับจากกองทุนประกันสังคมตามกฎหมายว่าด้วยการประกันสังคม (๒๖) เงินได้จากการโอนกรรมสิทธิ์หรือสิทธิครอบครองในอสังหาริมทรัพย์โดยไม่มีค่าตอบแทนให้แก่บุตรชอบด้วยกฎหมายซึ่งไม่รวมถึงบุตรบุญธรรม เฉพาะเงินได้จากการโอนให้แก่บุตรชอบด้วยกฎหมายนั้น ในส่วนที่ไม่เกินยี่สิบล้านบาทต่อบุตรหนึ่งคนตลอดปีภาษีนั้น (๒๗) เงินได้ที่ได้รับจากการอุปการะหรือจากการให้โดยเสน่หาจากบุพการี ผู้สืบสันดาน หรือคู่สมรส เฉพาะเงินได้ในส่วนที่ไม่เกินยี่สิบล้านบาทตลอดปีภาษีนั้น (๒๘) เงินได้ที่ได้รับจากการอุปการะโดยหน้าที่ธรรมจรรยาหรือจากการให้โดยเสน่หาเนื่องในพิธีหรือตามโอกาสแห่งขนบธรรมเนียมประเพณี ทั้งนี้ จากบุคคลซึ่งมิใช่บุพการี ผู้สืบสันดาน หรือคู่สมรส เฉพาะเงินได้ในส่วนที่ไม่เกินสิบล้านบาทตลอดปีภาษีนั้น (๒๙) เงินได้ที่ได้รับจากการให้โดยเสน่หาที่ผู้ให้แสดงเจตนาหรือเห็นได้ว่ามีความประสงค์ให้ใช้เพื่อประโยชน์ในกิจการศาสนา กิจการศึกษา หรือกิจการสาธารณประโยชน์ ตามหลักเกณฑ์ และเงื่อนไขที่กำหนดในกฎกระทรวง
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
มาตรา 48 ประมวลรัษฎากร
ข้อความเต็ม
เงินได้พึงประเมินต้องเสียภาษีเงินได้ดังต่อไปนี้ (๑) เงินได้พึงประเมินเมื่อได้หักตามมาตรา ๔๒ ทวิ ถึงมาตรา ๔๗ หรือมาตรา ๕๗ เบญจ แล้ว เหลือเท่าใดเป็นเงินได้สุทธิ ต้องเสียภาษีในอัตราที่กำหนดในบัญชีอัตราภาษีเงินได้ท้ายหมวดนี้ (๒) สำหรับผู้มีเงินได้พึงประเมินตั้งแต่ ๑๒๐,๐๐๐ บาทขึ้นไป การคำนวณภาษีตาม (๑) ให้เสียไม่น้อยกว่าร้อยละ ๐.๕ ของยอดเงินได้พึงประเมิน การนับจำนวนเงินได้พึงประเมินตาม (๒) ไม่รวมถึงเงินได้พึงประเมินตามมาตรา ๔๐ (๑) (๓) ผู้มีเงินได้จะเลือกเสียภาษีในอัตราร้อยละ ๑๕.๐ ของเงินได้โดยไม่ต้องนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ก็ได้ สำหรับเงินได้ตามมาตรา ๔๐ (๔) (ก) และ (ช) ดังต่อไปนี้ (ก) ดอกเบี้ยพันธบัตร ดอกเบี้ยเงินฝากธนาคารในราชอาณาจักร ดอกเบี้ยเงินฝากสหกรณ์ ดอกเบี้ยหุ้นกู้ ดอกเบี้ยตั๋วเงินที่ได้จากบริษัทหรือห้างหุ้นส่วนนิติบุคคลหรือนิติบุคคลอื่น ดอกเบี้ยเงินกู้ยืมที่ได้จากบริษัทหรือห้างหุ้นส่วนนิติบุคคลหรือนิติบุคคลอื่น ดอกเบี้ยที่ได้จากสถาบันการเงินที่มีกฎหมายโดยเฉพาะของประเทศไทยจัดตั้งขึ้นสำหรับให้กู้ยืมเงินเพื่อส่งเสริมเกษตรกรรม พาณิชยกรรม หรืออุตสาหกรรม (ข) ผลต่างระหว่างราคาไถ่ถอนกับราคาจำหน่ายตั๋วเงิน หรือตราสารแสดงสิทธิในหนี้ที่บริษัทหรือห้างหุ้นส่วนนิติบุคคลหรือนิติบุคคลอื่นเป็นผู้ออก (ค) ผลประโยชน์ที่ได้จากการโอนพันธบัตร หุ้นกู้ หรือตั๋วเงิน หรือตราสารแสดงสิทธิในหนี้ที่บริษัทหรือห้างหุ้นส่วนนิติบุคคลหรือนิติบุคคลอื่นเป็นผู้ออก ทั้งนี้ เฉพาะที่ตีราคาเป็นเงินได้เกินกว่าที่ลงทุน ผู้มีเงินได้ซึ่งเป็นผู้อยู่ในประเทศไทยจะเลือกเสียภาษีในอัตราร้อยละ ๑๐.๐ ของเงินได้โดยไม่ต้องนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ก็ได้สำหรับเงินได้ตามมาตรา ๔๐ (๔) (ข) ที่ได้รับจากบริษัทหรือห้างหุ้นส่วนนิติบุคคลที่ตั้งขึ้นตามกฎหมายไทย หรือสถาบันการเงินที่มีกฎหมายโดยเฉพาะของประเทศไทยจัดตั้งขึ้นสำหรับให้กู้ยืมเงินเพื่อส่งเสริมเกษตรกรรม พาณิชยกรรม หรืออุตสาหกรรม (๔) ผู้มีเงินได้จะเลือกเสียภาษีโดยไม่ต้องนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ก็ได้ เฉพาะเงินได้ตามมาตรา ๔๐ (๘) ที่ได้รับจากการขายอสังหาริมทรัพย์อันเป็นมรดกหรืออสังหาริมทรัพย์ที่ได้มาโดยมิได้มุ่งในทางการค้าหรือหากำไร ดังต่อไปนี้ (ก) เงินได้จากการขายอสังหาริมทรัพย์อันเป็นมรดกหรืออสังหาริมทรัพย์ที่ได้รับจากการให้โดยเสน่หา ให้หักค่าใช้จ่ายร้อยละ ๕๐ ของเงินได้ เหลือเท่าใดถือเป็นเงินได้สุทธิแล้วหารด้วยจำนวนปีที่ถือครองได้ผลลัพธ์เป็นเงินเท่าใด ให้คำนวณภาษีตามอัตราภาษีเงินได้ ได้เท่าใดให้คูณด้วยจำนวนปีที่ถือครองผลลัพธ์ที่ได้เป็นเงินภาษีที่ต้องเสีย (ข) เงินได้จากการขายอสังหาริมทรัพย์ที่ได้มาโดยทางอื่นนอกจาก (ก) ให้หักค่าใช้จ่ายได้ตามที่กำหนดโดยพระราชกฤษฎีกา เหลือเท่าใดถือเป็นเงินได้สุทธิ แล้วหารด้วยจำนวนปีที่ถือครอง ได้ผลลัพธ์เป็นเงินเท่าใด ให้คำนวณภาษีตามอัตราภาษีเงินได้ ได้เท่าใดให้คูณด้วยจำนวนปีที่ถือครอง ผลลัพธ์ที่ได้เป็นเงินภาษีที่ต้องเสีย ในกรณีที่เสียภาษีโดยไม่นำไปรวมคำนวณภาษีตาม (๑) และ (๒) เมื่อคำนวณภาษีแล้วต้องเสียไม่เกินร้อยละ ๒๐ ของราคาขาย ในกรณีที่เสียภาษีโดยนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ให้หักค่าใช้จ่ายร้อยละ ๕๐ ของเงินได้ตาม (ก) หรือตามที่กำหนดโดยพระราชกฤษฎีกาตาม (ข) แล้วแต่กรณี เหลือเท่าใดนำไปรวมคำนวณภาษีกับเงินได้อย่างอื่น คำว่า “จำนวนปีที่ถือครอง” ใน (ก) หรือ (ข) หมายถึงจำนวนปีนับตั้งแต่ปีที่ได้กรรมสิทธิ์หรือสิทธิครอบครองในอสังหาริมทรัพย์ ถึงปีที่โอนกรรมสิทธิ์หรือสิทธิครอบครองในอสังหาริมทรัพย์นั้น ถ้าเกินสิบปีให้นับเพียงสิบปี และเศษของปีให้นับเป็นหนึ่งปี (๔/๑) ผู้มีเงินได้จะเลือกเสียภาษีในอัตราร้อยละ ๕ ของเงินได้ส่วนที่เกินยี่สิบล้านบาท โดยไม่ต้องนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ก็ได้ สำหรับเงินได้ตามมาตรา ๔๐ (๘) ที่เป็นเงินได้จากการโอนกรรมสิทธิ์หรือสิทธิครอบครองในอสังหาริมทรัพย์โดยไม่มีค่าตอบแทนให้แก่บุตรชอบด้วยกฎหมายซึ่งไม่รวมถึงบุตรบุญธรรม ที่ไม่ได้รับยกเว้นตามมาตรา ๔๒ (๒๖) (๕) ผู้มีเงินได้จะเลือกเสียภาษีโดยไม่ต้องนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ก็ได้ สำหรับเงินได้พึงประเมินตามมาตรา ๔๐ (๑) และ (๒) ซึ่งเป็นเงินที่นายจ้างจ่ายให้ครั้งเดียวเพราะเหตุออกจากงาน ซึ่งได้คำนวณจ่ายจากระยะเวลาที่ทำงานและได้จ่ายตามหลักเกณฑ์ วิธีการ และเงื่อนไขที่อธิบดีกำหนด โดยให้นำเงินได้พึงประเมินดังกล่าวหักค่าใช้จ่ายเป็นจำนวนเท่ากับ ๗,๐๐๐ บาท คูณด้วยจำนวนปีที่ทำงานแต่ไม่เกินเงินได้พึงประเมิน เหลือเท่าใดให้หักค่าใช้จ่ายอีกร้อยละ ๕๐ ของเงินที่เหลือนั้นแล้วคำนวณภาษีตามอัตราภาษีเงินได้ ในกรณีเงินได้พึงประเมินดังกล่าวจ่ายในลักษณะเงินบำเหน็จจำนวนหนึ่งและเงินบำนาญอีกจำนวนหนึ่ง ให้ถือว่าเฉพาะเงินที่จ่ายในลักษณะเงินบำเหน็จเป็นเงินซึ่งนายจ้างจ่ายให้ครั้งเดียวเพราะเหตุออกจากงานและให้ลดค่าใช้จ่ายจำนวน ๗,๐๐๐ บาท ลงเหลือ ๓,๕๐๐ บาท จำนวนปีที่ทำงานตามวรรคหนึ่ง ในกรณีเงินบำเหน็จหรือเงินอื่นใดในลักษณะเดียวกัน ที่ทางราชการจ่าย ให้ถือจำนวนปีที่ใช้เป็นเกณฑ์คำนวณเงินบำเหน็จหรือเงินอื่นในลักษณะเดียวกันนั้นตามกฎหมาย ระเบียบ หรือข้อบังคับของทางราชการ ในการคำนวณจำนวนปีที่ทำงาน นอกจากกรณีตามวรรคสาม เศษของปี ถ้าถึงหนึ่งร้อยแปดสิบสามวันให้ถือเป็นหนึ่งปี ถ้าไม่ถึงหนึ่งร้อยแปดสิบสามวันให้ปัดทิ้ง (๖) ผู้มีเงินได้จะเลือกเสียภาษีในอัตราร้อยละ ๕ ของเงินได้ส่วนที่เกินยี่สิบล้านบาท โดยไม่ต้องนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ก็ได้ สำหรับเงินได้ตามมาตรา ๔๐ (๘) ที่ได้รับจากการอุปการะหรือจากการให้โดยเสน่หาจากบุพการี ผู้สืบสันดาน หรือคู่สมรส ที่ไม่ได้รับยกเว้นตามมาตรา ๔๒ (๒๗) (๗) ผู้มีเงินได้จะเลือกเสียภาษีในอัตราร้อยละ ๕ ของเงินได้ส่วนที่เกินสิบล้านบาท โดยไม่ต้องนำไปรวมคำนวณภาษีตาม (๑) และ (๒) ก็ได้ สำหรับเงินได้ตามมาตรา ๔๐ (๘) ที่ได้รับจากการอุปการะโดยหน้าที่ธรรมจรรยาหรือจากการให้โดยเสน่หาเนื่องในพิธีหรือตามโอกาสแห่งขนบธรรมเนียมประเพณี ทั้งนี้ จากบุคคลซึ่งมิใช่บุพการี ผู้สืบสันดาน หรือคู่สมรส ที่ไม่ได้รับยกเว้นตามมาตรา ๔๒ (๒๘)
ตรงตามข้อความในราชกิจจานุเบกษา / สำนักงานคณะกรรมการกฤษฎีกา (Verbatim from the Royal Gazette / Office of the Council of State)
Français
Article 1686
Un trust constitué directement ou indirectement par testament, ou par tout acte juridique produisant effet du vivant de son auteur ou après son décès, est sans effet, sauf s'il est constitué en vertu d'une disposition légale autorisant la création de trusts.
résumé non officiel
Article 37 Act on Conflict of Laws B.E. 2481
La succession immobilière est régie par la loi du lieu de situation du bien.
résumé non officiel
Article 38 Act on Conflict of Laws B.E. 2481
Pour les meubles, la succession légale ou testamentaire est régie par la loi du domicile du défunt au moment du décès.
résumé non officiel
Article 42 Revenue Code
Exonérés: frais de mission réels; indemnités publiques; certaines primes; intérêts d'épargne (bancaires jusqu'à 10 000 bahts par an); vente de biens meubles non commerciale; héritages; prix et loteries publics; indemnités et assurances; sécurité sociale; transmissions et dons familiaux (20 millions), coutumiers (10 millions) ou caritatifs; cas par règlement ministériel.
résumé non officiel
Article 48 Revenue Code
Revenu net au barème, minimum 0,5 % dès 120 000 bahts hors salaires. Options séparées, notamment 15 % sur intérêts, 10 % sur dividendes thaïlandais pour résidents, immobilier hérité ou non commercial plafonné à 20 % du prix, indemnité de départ, 5 % sur dons excédant 20 ou 10 millions.
résumé non officiel
Sources
- Code civil et commercial, Office of the Council of State, consulté le 31 octobre 2026
- Act on Conflict of Laws B.E. 2481, consulté le 31 octobre 2026
- Revenue Code, consulté le 2 novembre 2026
Comment les personnes vivant en Thaïlande peuvent utiliser des fiducies étrangères
Vous pouvez créer une fiducie dans une juridiction favorable aux fiducies et y transférer des actifs non thaïlandais. Singapour, Jersey, l'île de Man, le Royaume-Uni et les États-Unis sont des options intéressantes. Choisissez le lieu qui correspond à votre résidence fiscale, à la nature de vos actifs et à vos objectifs familiaux, tout en tenant compte des implications fiscales thaïlandaises.
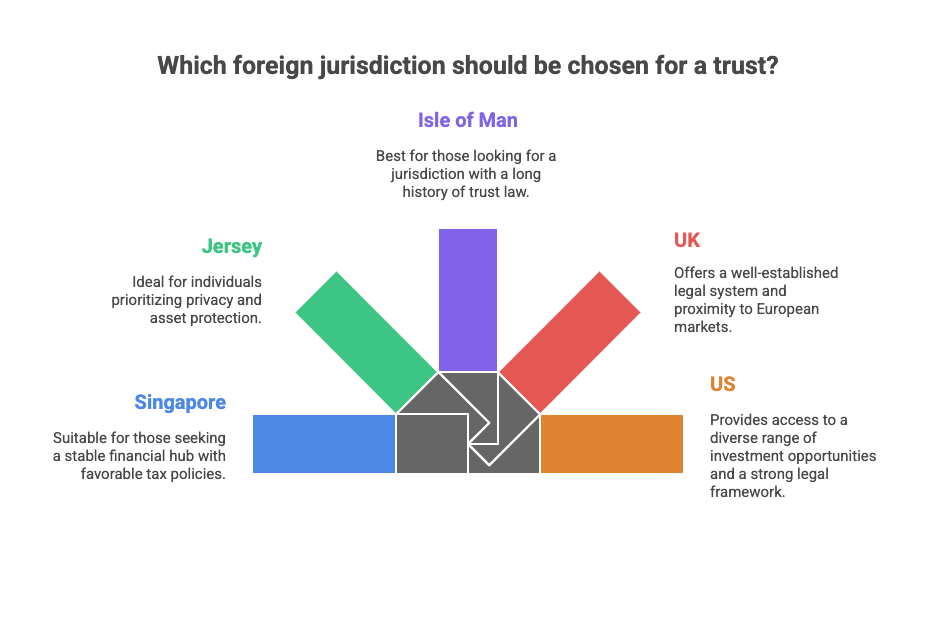
Les actifs éligibles à une fiducie étrangère en vertu du droit thaïlandais peuvent offrir des avantages considérables.
- Comptes bancaires et portefeuilles d'investissement détenus hors de Thaïlande
- Immobilier situé à l'étranger
- Participations dans des sociétés étrangères et autres intérêts commerciaux
- Propriété intellectuelle et redevances provenant de l'extérieur de la Thaïlande
Avantages d'une fiducie étrangère associée à des outils thaïlandais
- Évite les procédures d'homologation de testament dans plusieurs pays et accélère les distributions
- Assure la continuité si le constituant devient incapable
- Consolide la gestion des actifs transfrontaliers pour les expatriés en Thaïlande.
Depuis le 1er janvier 2024, revenus étrangers qu'une Résident fiscal thaïlandais Les revenus provenant de la Thaïlande sont imposés dans l’année de leur introduction, quelle que soit la date de cette introduction. Cela ne s’applique que pour les revenus provenant du 1er janvier 2024 ou après cette date, dans une année où la personne était résidente en Thaïlande ; les revenus provenant de périodes antérieures à 2024 ne sont pas concernés par cette règle (Instructions du Département des recettes Por.161/2566 et Por.162/2566, qui constituent des directives destinées aux agents des recettes plutôt que des amendements au Code des recettes). Cela affecte les distributions de fonds versées en Thaïlande par des résidents fiscaux thaïlandais. Vous devez classer les distributions selon leur type lorsque vous le pouvez. Suivez les transferts de fonds et établissez un plan de retenue et de déclaration. Fais-le avant le premier transfert en 2024 ou plus tard.
Impôt sur les successions s'applique aux successions des personnes décédées après l'entrée en vigueur de la loi B.E. 2558 sur l'impôt sur les successions, au début de 2016 (article 3(1)). Le montant imposable est la part supérieure à 100 millions de THB que chaque héritier reçoit de chaque défunt (article 12). Le taux est de 10 %, réduit à 5 % pour les ascendants ou les descendants (article 16). Ce que reçoit le conjoint est exonéré (article 3(2)). La déclaration doit être déposée dans les 150 jours suivant la réception de l'héritage (article 17). Veuillez noter que les dons provenant d’ascendants, de descendants ou du conjoint sont exonérés de l’impôt sur le revenu des personnes physiques jusqu’à 20 millions de THB par année d’imposition (article 42(27) du Code des impôts) ; sur l’excédent, le bénéficiaire peut opter pour une imposition forfaitaire de 5 % au lieu de l’ajouter à son revenu imposable (article 48(6)). Les dons faits par d’autres personnes lors d’occasions coutumières sont exonérés jusqu’à 10 millions de THB par an (article 42(28)), avec la même option forfaitaire de 5 % sur l’excédent (article 48(7)).
Comment ThaiLawOnline peut vous aider
Chez ThaiLawOnline, je coordonne les services de planification successorale. Cela garantit la bonne intégration de votre fiducie étrangère et de vos documents thaïlandais.
Notre soutien comprend
- L'analyse de la juridiction est importante pour les expatriés afin de se conformer au droit fiscal thaïlandais et au droit international. Nous vous aidons à choisir la juridiction fiduciaire la plus adaptée et à vous mettre en relation avec des avocats étrangers.
- coordination internationaleNous collaborons avec des avocats et des experts étrangers de confiance pour mettre en place la fiducie correctement.
- Documents juridiques thaïlandais relatifs aux biens thaïlandais:
- Sur mesure : Le testament thaïlandais pour les actifs en Thaïlande. Consultez notre page sur Testament en Thaïlande
- Contrats d'usufruit lorsque cela est approprié en matière de droits d'usage de la propriété. Consultez notre analyse approfondie de contrat d'usufruit en Thaïlande.
- Contrats prénuptiaux lorsque la planification familiale fait partie des objectifs. Consultez notre article sur le Contrat prénuptial Thaïlande.
- La mise en place de structures d'entreprise ou immobilières, le cas échéant, peut s'avérer essentielle pour les expatriés qui gèrent leur patrimoine. Vous pouvez commencer par Avocat spécialisé en droit immobilier à Bangkok.
Nous ne sommes pas des avocats étrangers. Pour la création de la fiducie, nous collaborons avec des avocats qualifiés dans la juridiction choisie. Ainsi, votre acte de fiducie est conforme à la réglementation locale et s'articule avec vos documents thaïlandais.
Questions fréquentes
Est-il possible de créer une fiducie en Thaïlande ?
Pas pour la planification familiale ou patrimoniale. L’article 1686 du Code civil et commercial ne confère aucune valeur juridique à un fiducie à moins qu’elle ne soit créée en vertu d’une loi autorisant la création de fiducies. La seule loi de ce type est la Loi sur les fiducies pour les transactions sur le marché financier B.E. 2550, et au titre de son article 12, seule une personne morale peut créer une telle fiducie.
Un trust étranger peut-il posséder des biens immobiliers en Thaïlande ?
Ne placez pas les biens immobiliers thaïlandais sous une fiducie étrangère. La législation thaïlandaise ne prévoit pas de mécanisme permettant de faire enregistrer le titre de fiduciaire à cette fin. Gardez la fiducie étrangère pour les actifs non thaïlandais et utilisez des instruments thaïlandais, tels qu'un testament thaïlandais, pour les actifs situés en Thaïlande.
Les distributions de fonds en fiducie versées en Thaïlande sont-elles soumises à l’impôt ?
Ils peuvent l’être. Depuis le 1er janvier 2024, les revenus étrangers que les résidents fiscaux thaïlandais apportent en Thaïlande sont imposés dans l’année où ils sont perçus. Cela s’applique aux revenus provenant le 1er janvier 2024 ou après cette date, dans une année où la personne était résidente en Thaïlande.
La Thaïlande a-t-elle une taxe d'héritage ?
Oui. Cela s'applique à la partie supérieure à 100 millions de THB que chaque héritier reçoit de chaque défunt, soit 10 % réduits à 5 % pour les ascendants ou les descendants. Ce que le conjoint reçoit est exonéré de contribution, et la déclaration doit être effectuée dans les 150 jours suivant la réception de l'héritage.
Pourquoi combiner des fiducies étrangères avec la planification successorale thaïlandaise ?
L'utilisation d'une fiducie étrangère pour les actifs non thaïlandais et d'outils thaïlandais pour les actifs locaux offre une couverture complète.
- Compatibilité totale avec la juridiction: Chaque actif est géré conformément à la loi applicable. C’est important pour les expatriés afin de réduire leur impôt sur les successions.
- Moins de litigesDes documents clairs réduisent la confusion chez les héritiers.
- Connaissance des impôtsUne bonne planification permet de réduire les impôts globaux tout en restant en conformité avec la loi.
- efficacité pratique: Exécuteurs testamentaires et les fiduciaires ont des rôles et des étapes bien définis.
- Sécurité familialeVotre plan soutient vos proches au-delà des frontières.
Exemples concrets
Une personne résidant à Bangkok possède un appartement en Thaïlande, des comptes d'investissement à Singapour et une maison au Royaume-Uni.
- Un trust singapourien détient les actifs non thaïlandais.
- Un Le testament thaïlandais couvre le condo et les comptes bancaires thaïlandais.
- La désignation des bénéficiaires correspond au plan global.
- L'équipe coordonne le calendrier, les déclarations fiscales et les démarches pratiques dans chaque lieu.
Si vous résidez en Thaïlande et possédez des biens à l'étranger, je peux vous aider à élaborer un plan successoral simple et conforme à la loi. Contactez ThaiLawOnline pour découvrir nos services de planification successorale adaptés aux expatriés en Thaïlande. Les trusts en Thaïlande en tant que stratégie combinant des trusts étrangers et des outils successoraux thaïlandais. Nous recenserons vos actifs, choisirons la juridiction la plus adaptée et préparerons vos documents thaïlandais afin que l'ensemble fonctionne de manière cohérente.
Liens : SEC en Thaïlande
Actualités juridiques thaïlandaises, gratuites par courriel
Des mises à jour en anglais simple sur les changements législatifs thaïlandais concernant les étrangers : propriété, visas, mariage, affaires et testaments. Un court courriel par mois, envoyé par un cabinet d’avocats établi depuis 2006. Zéro spam, désabonnement possible à tout moment.